Category: Finance

  • How to Read Stock Charts: A Beginner’s Step-by-Step Guide

    How to Read Stock Charts: A Beginner’s Step-by-Step Guide

    A stock chart shows how a stock’s price has moved over a period of time. To read one, start with the timeframe and overall trend, then examine price levels, candlesticks, trading volume, and selected indicators. The goal is to understand what the chart is showing—not to assume it can predict exactly what happens next.

    If you’re new to stock charts, the amount of information on a typical chart can look overwhelming. Lines, candles, numbers, volume bars, indicators, and patterns can all appear at once.

    The good news is that you don’t need to understand everything immediately.

    A practical way to read a stock chart is to work through it in a consistent order:

    Timeframe → Trend → Key levels → Volume → Candlesticks → Indicators → Patterns → Context

    This guide explains each step in plain language and shows how the different pieces fit together.

    What Is a Stock Chart?

    A stock chart is a visual representation of a stock’s price movement over time. Depending on the chart type, it can also show information such as the opening price, highest price, lowest price, closing price, and trading volume.

    Most stock charts have two basic axes:

    • Horizontal axis: represents time.
    • Vertical axis: represents price.

    For example, a daily chart may show one trading day at a time, while an intraday chart could show price movement minute by minute.

    A chart helps you see historical price behavior quickly. It can show whether price has generally moved upward, downward, or sideways and where important price levels have developed.

    However, a chart does not contain every factor that can affect a stock. Company earnings, economic conditions, interest rates, news, management decisions, valuation, and other fundamental factors may also influence prices.

    How to Read a Stock Chart Step by Step

    You can make stock chart analysis much easier by following the same sequence every time.

    Start With the Timeframe

    Before interpreting a chart, check its timeframe.

    A chart can look completely different depending on whether you’re viewing:

    • One-minute candles
    • Five-minute candles
    • One-hour candles
    • Daily candles
    • Weekly candles
    • Monthly candles

    A short timeframe shows smaller price movements, while a longer timeframe can make broader trends easier to see.

    For beginners, starting with a daily or weekly chart can make it easier to understand the bigger picture before looking at shorter-term movements.

    Check the Overall Trend

    Next, ask a simple question:

    Is the stock moving generally upward, downward, or sideways?

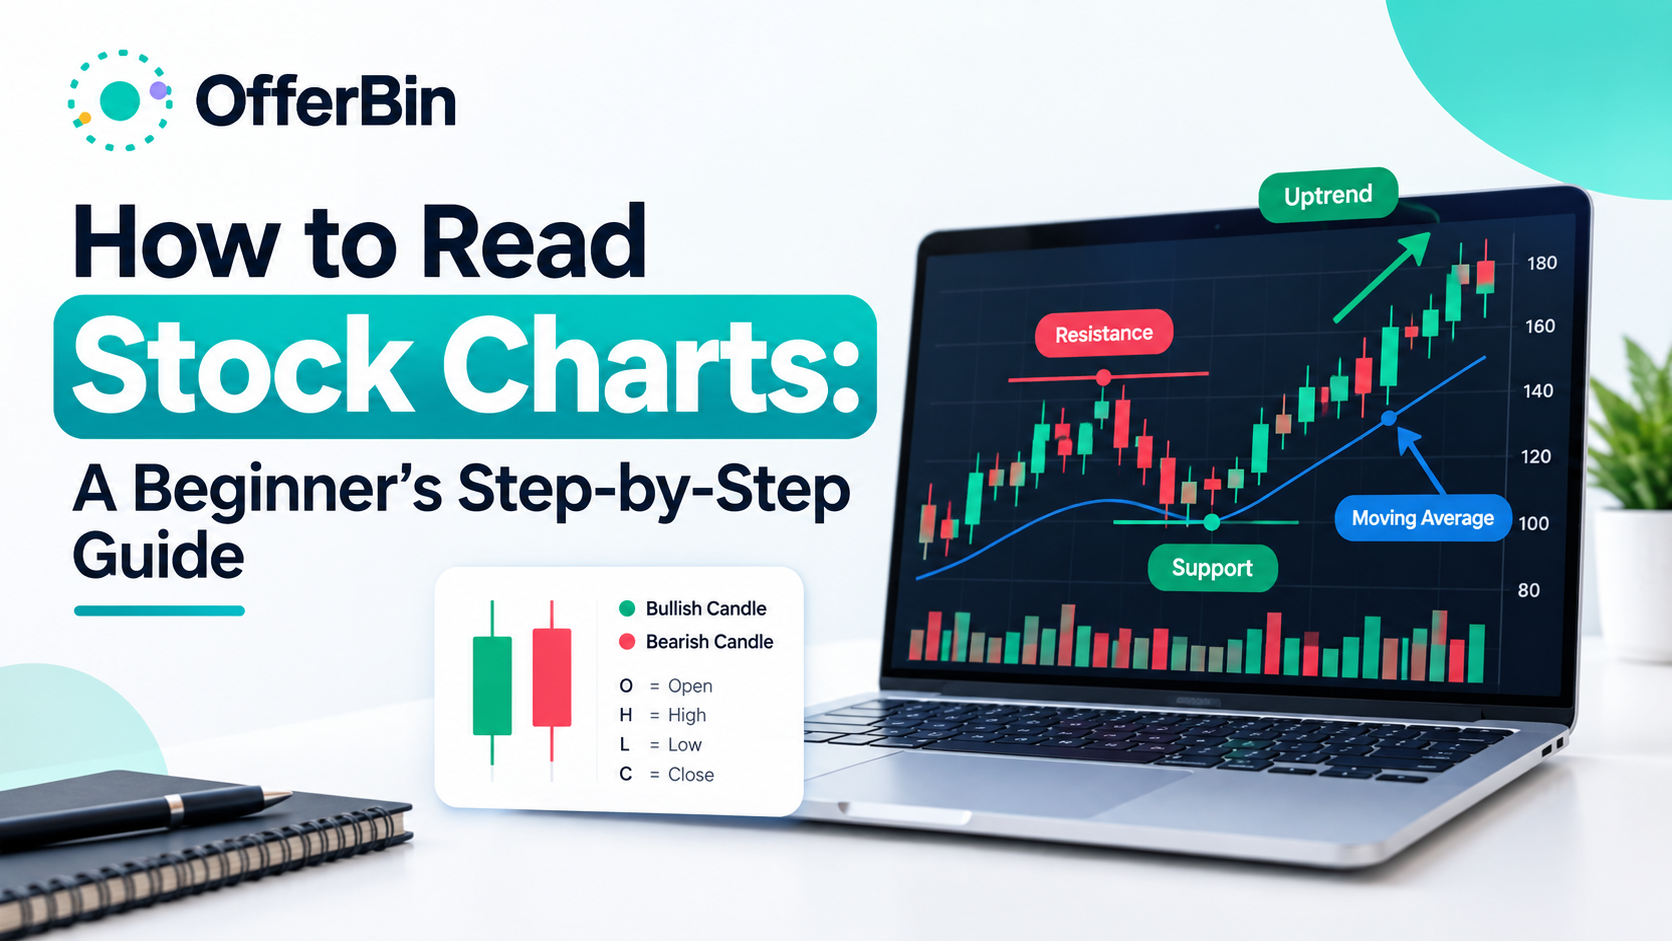
    An uptrend commonly features a sequence of higher highs and higher lows.

    A downtrend commonly features lower highs and lower lows.

    A sideways market moves within a relatively defined range without a clear sustained upward or downward direction.

    Don’t determine the trend from one candle. Look at a meaningful section of the chart and consider how the sequence of highs and lows is developing.

    Identify Support and Resistance

    After identifying the trend, look for important price areas.

    Support is an area where buying interest has previously helped slow or stop a decline.

    Resistance is an area where selling pressure has previously helped slow or stop an advance.

    These are better understood as zones rather than perfectly precise lines. Price can move slightly through a level before reversing, and previous support can sometimes become resistance after a breakdown.

    Look at Trading Volume

    Volume tells you how many shares changed hands during a particular period.

    Price and volume can provide useful context when viewed together.

    For example:

    • Rising price with increasing volume can indicate stronger participation.
    • A price move on unusually low volume may deserve additional scrutiny.
    • High volume during a breakout can provide additional context.
    • A sudden volume spike can accompany important news or significant price movement.

    Volume does not automatically confirm that a move will continue. It is one piece of information among several.

    Read the Latest Candlesticks

    Once you understand the broader trend, examine the latest candles.

    Look at:

    • Candle direction
    • Candle body size
    • Upper wick
    • Lower wick
    • Position relative to recent price levels
    • Volume during the move

    A single candle rarely provides enough information by itself. Its meaning depends heavily on where it appears on the chart and what price was doing beforehand.

    Check a Small Number of Indicators

    Indicators can help organize price information, but more indicators do not necessarily produce better analysis.

    Common examples include:

    • Moving averages
    • Relative Strength Index (RSI)
    • Moving Average Convergence Divergence (MACD)

    For beginners, it can be more useful to understand one or two indicators properly than to place a large collection of indicators on the same chart.

    Look for Chart Patterns

    Finally, you can consider whether a recognizable chart pattern is developing.

    Examples include:

    • Double tops
    • Double bottoms
    • Head and shoulders
    • Triangles
    • Flags

    Patterns should be treated as potential interpretations rather than guaranteed forecasts. Context, volume, timeframe, and the broader market can all affect how a pattern develops.

    Stock Chart Types Explained

    Different chart types present price information in different ways.

    Chart typeWhat it showsBest use
    Line chartUsually closing prices connected over timeSeeing the broad trend
    Bar chartOpen, high, low and closeDetailed price analysis
    Candlestick chartOpen, high, low and close in an easy-to-read visual formatPrice action and chart analysis

    Line Charts

    Line charts are among the simplest stock charts.

    A line connects a series of prices—often closing prices—to show how the stock moved over time.

    They’re useful when you want to quickly see the overall direction without being distracted by individual intraday movements.

    Bar Charts

    A traditional price bar contains information about the stock’s:

    • Open
    • High
    • Low
    • Close

    This is commonly abbreviated as OHLC.

    The bar’s high and low show the trading range for that period, while small horizontal marks indicate the opening and closing prices.

    Candlestick Charts

    Candlestick charts contain the same basic OHLC information but present it in a more visual format.

    Each candle can quickly show:

    • Where price opened
    • Where price closed
    • The highest price reached
    • The lowest price reached

    This makes candlestick charts particularly popular for technical analysis.

    How to Read Candlestick Charts

    A candlestick has two main visual components:

    Body: shows the relationship between the opening and closing prices.

    Wicks or shadows: show prices reached above and below the candle’s body.

    The exact colors depend on the charting platform, but many platforms use green for a period where the closing price was higher than the opening price and red for a period where the closing price was lower.

    What Do Green and Red Candles Mean?

    A green candle generally means the closing price was above the opening price for that period.

    A red candle generally means the closing price was below the opening price.

    The color alone does not tell you what happens next.

    For example, a large green candle near resistance can mean something very different from a large green candle breaking above a long-established trading range.

    What Do the Wicks Mean?

    The upper wick shows how high price moved during the period before closing.

    The lower wick shows how low price moved.

    Long wicks can show that price moved significantly away from the eventual closing area during that period.

    Again, context matters. A long lower wick near a support zone has a different context from a long lower wick during a strong downtrend.

    How to Identify Trends on Stock Charts

    Trend analysis is one of the most useful starting points when reading a stock chart.

    Uptrend

    An uptrend generally develops through a series of:

    Higher highs + higher lows

    The stock is repeatedly reaching higher price levels while pullbacks are holding above previous lows.

    Downtrend

    A downtrend generally develops through:

    Lower highs + lower lows

    Rallies fail to reach previous highs, while declines continue to establish lower lows.

    Sideways Trend

    A stock may also trade sideways.

    In this situation, price repeatedly moves between a relatively defined upper and lower area without establishing a sustained directional trend.

    Sideways markets are sometimes described as ranges or consolidations.

    Why Higher Highs and Higher Lows Matter

    Looking at highs and lows can be more useful than simply asking whether a stock is “going up.”

    A stock may rise sharply for several days but still be part of a broader downtrend if its longer-term structure continues to produce lower highs and lower lows.

    This is why timeframe matters.

    Support and Resistance Explained

    Support and resistance are common concepts in stock chart analysis.

    What Is Support?

    Support is a price area where previous selling pressure has been met by enough buying activity to slow or reverse a decline.

    Support isn’t guaranteed to hold.

    If selling pressure becomes strong enough, price can move below the area.

    What Is Resistance?

    Resistance is a price area where previous upward movement has encountered selling pressure.

    A stock can break above resistance, remain below it, or briefly move above it and then fall back.

    How to Identify Support and Resistance on a Chart

    Look for areas where price has repeatedly:

    • Reversed upward
    • Reversed downward
    • Paused before continuing
    • Consolidated
    • Reacted strongly

    The more frequently price reacts around an area, the more noticeable that zone may become.

    But there is no universal rule that makes a particular support or resistance level certain to hold.

    Support and Resistance Zones

    It’s often better to think in terms of zones rather than exact numbers.

    For example, if a stock repeatedly reacts between $48 and $50, treating $49.00 as an exact dividing line may create a false sense of precision.

    A broader zone can better represent the historical price behavior.

    How to Read Stock Volume

    Volume measures the number of shares traded during a particular period.

    It is usually displayed below the main price chart as vertical bars.

    Volume can help provide context for price movements.

    Rising Price and Volume

    If price rises while volume also increases, the move is occurring alongside greater trading activity.

    That may provide useful confirmation, but it does not guarantee that the trend will continue.

    Falling Price and Volume

    A decline accompanied by elevated volume can indicate significant participation during the move.

    Again, the information should be interpreted alongside the broader trend and price structure.

    Volume During Breakouts

    Volume is often watched when price moves beyond an established resistance or support area.

    A breakout accompanied by noticeably higher volume may attract more attention than a move through the same level on unusually low volume.

    However, breakouts can fail.

    A move above resistance that quickly falls back into the previous range is sometimes described as a false breakout.

    Moving Averages and Other Stock Chart Indicators

    Indicators transform or organize price and volume data to help traders examine particular aspects of market behavior.

    They should not be treated as automatic buy or sell signals.

    Simple Moving Average

    A Simple Moving Average (SMA) calculates the average price over a specified number of periods.

    For example, a 50-day SMA uses the prices from the relevant 50 trading days to calculate an average that changes as new data arrives.

    Moving averages can help smooth short-term price fluctuations and make broader trends easier to observe.

    Exponential Moving Average

    An Exponential Moving Average (EMA) gives greater weight to more recent prices than a simple moving average.

    As a result, it can respond more quickly to recent price changes.

    Relative Strength Index

    The Relative Strength Index (RSI) is a momentum indicator commonly displayed on a scale from 0 to 100.

    It is often used to assess the strength of recent price movements and identify potentially overextended conditions.

    An RSI reading should not be interpreted in isolation or treated as proof that a stock must reverse.

    MACD

    The Moving Average Convergence Divergence (MACD) is another momentum and trend-related indicator.

    It compares moving averages and can help users examine changes in momentum and trend behavior.

    As with other indicators, the MACD is most useful when understood in the context of the underlying price action.

    Avoid Indicator Overload

    A common beginner mistake is adding many indicators because the chart looks more sophisticated.

    More information can actually make a chart harder to interpret.

    Start with the basic price structure. Add an indicator only when you understand what question it is helping you answer.

    Common Stock Chart Patterns

    Chart patterns describe recurring formations in price data.

    They can be useful for organizing what you see, but patterns are not guarantees of future price direction.

    Double Top

    A double top occurs when price reaches a similar high on two occasions and struggles to move beyond the area.

    The pattern is generally interpreted in the context of what happens after the second attempt.

    Double Bottom

    A double bottom is broadly the opposite structure, where price tests a similar low twice before moving away from the area.

    Head and Shoulders

    A head-and-shoulders structure typically contains:

    • A first peak
    • A higher central peak
    • A third peak that is lower than the central peak

    The lows between these peaks are often connected conceptually by a neckline.

    Triangles

    Triangle patterns form when price moves within converging boundaries.

    Common descriptions include:

    • Ascending triangle
    • Descending triangle
    • Symmetrical triangle

    The eventual direction is not guaranteed simply because a triangle appears.

    Flags

    Flag patterns are generally short-term consolidation structures that occur after a noticeable price movement.

    As with all chart patterns, context is important.

    A Simple Stock Chart Analysis Example

    Imagine you’re looking at a hypothetical daily stock chart.

    The first thing you notice is that price has been producing higher highs and higher lows over several weeks.

    That suggests an upward trend.

    Next, you identify a price zone where previous pullbacks stopped. That becomes an area of potential support.

    You also identify a higher price area where previous advances struggled. That’s a potential resistance zone.

    Then you examine volume.

    The latest upward move occurred with higher-than-usual volume, giving you additional information about participation during the move.

    You then inspect the most recent candles. Instead of focusing on one candle, you compare the latest candles with the surrounding price action.

    Finally, you look at a moving average to see whether it provides useful additional context.

    The result is not a prediction.

    Instead, you’ve built a structured description of the chart:

    • Timeframe: Daily
    • Trend: Upward
    • Structure: Higher highs and higher lows
    • Support: Identified below recent price
    • Resistance: Identified above recent price
    • Volume: Elevated during the recent move
    • Candles: Reviewed in context
    • Indicator: Used as supporting information

    This is a much more useful way to approach stock chart analysis than trying to find one “magic” signal.

    Common Mistakes Beginners Make

    Looking at Only One Candle

    One candle rarely explains the entire market structure.

    Always consider surrounding price action.

    Ignoring the Timeframe

    A stock can look bullish on a five-minute chart while looking bearish on a weekly chart.

    Always know which timeframe you’re analyzing.

    Using Too Many Indicators

    A chart covered in indicators can create confusion rather than clarity.

    Start with price and volume before adding additional tools.

    Treating Patterns as Guarantees

    A chart pattern is an interpretation of historical price behavior.

    It is not a guarantee of future performance.

    Ignoring Volume

    Price can tell you where the market moved. Volume can provide additional context about trading activity during that move.

    Assuming Support or Resistance Must Hold

    Support and resistance are areas of historical price reaction, not permanent barriers.

    Confusing Technical Analysis With Fundamental Analysis

    A chart primarily shows market data such as price and volume.

    It does not automatically tell you:

    • Whether a company is profitable
    • Whether its valuation is attractive
    • Whether revenue is growing
    • Whether management is effective
    • Whether a product will succeed

    Those questions require other forms of research.

    Stock Chart Reading Checklist

    Before drawing conclusions from a stock chart, ask:

    • What timeframe am I viewing?
    • What does the broader trend look like?
    • Are highs and lows rising or falling?
    • Where are the major support zones?
    • Where are the major resistance zones?
    • What is trading volume doing?
    • What do the latest candlesticks show?
    • Is there a recognizable chart pattern?
    • Are indicators actually adding useful information?
    • Is the broader market affecting the stock?
    • Am I interpreting a possibility as if it were a certainty?
    • What important information isn’t visible on the chart?

    This checklist can help prevent you from focusing too heavily on one signal.

    Can Stock Charts Predict Future Prices?

    No chart can guarantee what a stock will do next.

    Stock charts are primarily tools for examining historical price and volume behavior. Technical analysis can help users identify trends, levels, patterns and changes in momentum, but those observations do not remove uncertainty.

    Future prices can be affected by information that isn’t visible on a chart, including company results, economic data, interest rates, news, regulations and unexpected events.

    For that reason, chart analysis is better understood as a method of interpreting market data than as a reliable prediction machine.

    Technical Analysis vs. Fundamental Analysis

    Technical and fundamental analysis approach markets from different angles.

    Technical analysisFundamental analysis
    Focuses heavily on price and volumeFocuses on business and economic factors
    Uses charts and indicatorsUses financial statements, valuation and business information
    Examines historical market behaviorExamines underlying financial and economic conditions
    Often emphasizes trends and patternsOften emphasizes earnings, cash flow and valuation

    These approaches don’t necessarily have to be treated as mutually exclusive. They answer different questions.

    How to Get Better at Reading Stock Charts

    The best way to improve is to practice interpreting charts systematically.

    Start with the basics:

    1. Choose a timeframe.
    2. Identify the overall trend.
    3. Mark obvious support and resistance zones.
    4. Examine volume.
    5. Read the latest candlesticks.
    6. Add only the indicators you understand.
    7. Look for patterns.
    8. Write down what the chart actually shows.
    9. Separate observations from assumptions.
    10. Review what happened afterward without changing your original interpretation.

    That last step is especially useful for learning. It helps you evaluate whether your interpretation was supported by the information available at the time rather than judging it only from hindsight.

    FAQs About Reading Stock Charts

    How do you read stock charts for beginners?

    Start by identifying the timeframe and overall trend. Then examine higher highs and lower lows, support and resistance, trading volume, candlesticks and a small number of useful indicators. Focus on the complete price structure rather than trying to interpret one candle or indicator in isolation.

    What do the lines on a stock chart mean?

    Lines can represent different types of information. The main price line may connect closing prices, while other lines may represent moving averages, trendlines, support or resistance. Always check the chart legend or indicator label to determine exactly what a particular line represents.

    What do green and red candles mean?

    On many charting platforms, a green candle means the closing price was higher than the opening price, while a red candle means the closing price was lower than the opening price. Color conventions can vary, so check your charting platform’s settings.

    What are OHLC prices?

    OHLC stands for Open, High, Low and Close. These four values describe the opening price, highest price, lowest price and closing price for a specific trading period.

    How do you identify an uptrend?

    An uptrend generally features a sequence of higher highs and higher lows. Rather than relying on one upward move, look at the broader structure of the chart and consider the timeframe you’re analyzing.

    How do you identify support and resistance?

    Look for price areas where the stock has repeatedly paused, reversed or struggled to move through. Support generally refers to areas where declines have previously slowed, while resistance refers to areas where advances have previously encountered selling pressure.

    What does volume tell you on a stock chart?

    Volume shows how many shares were traded during a particular period. It can provide context for price movements, including whether a breakout or decline occurred alongside unusually high trading activity.

    What is the best timeframe for reading stock charts?

    There is no single best timeframe for everyone. The appropriate timeframe depends on the question being analyzed. Longer timeframes can help reveal broader trends, while shorter timeframes show more detailed price movements.

    Which indicators should beginners use?

    Beginners can start by understanding basic tools such as moving averages, RSI and MACD. The important point is not to use as many indicators as possible, but to understand what each indicator measures and how it complements the price chart.

    Can stock charts predict stock prices?

    No. Charts can help analyze historical price and volume behavior, but they cannot guarantee future price movements. Market prices can change because of company-specific, economic, political, regulatory and other unexpected factors.

    Final Takeaway

    Learning how to read stock charts becomes easier when you stop trying to interpret everything at once.

    Start with the timeframe, then examine the trend, support and resistance, volume, and candlesticks. After that, use indicators and chart patterns as supporting information rather than treating them as guaranteed signals.

    The most useful question isn’t simply, “What pattern is this?”

    It’s:

    “What is the chart actually showing, what evidence supports that interpretation, and what remains uncertain?”

    That approach can help you read stock charts more systematically while avoiding many of the common mistakes beginners make.
  • Micro vs E-mini Futures: Contract Size, Tick Value & Risk Explained

    Micro vs E-mini Futures: Contract Size, Tick Value & Risk Explained

    If you’re comparing Micro vs E-mini futures, the biggest difference is contract size. Micro E-mini futures generally represent one-tenth the contract size of their corresponding E-mini contracts. That means the underlying market can be the same, while the dollar value of each point and tick is much smaller.

    For example, one E-mini S&P 500 (ES) contract uses a $50 multiplier, while one Micro E-mini S&P 500 (MES) contract uses a $5 multiplier. At an S&P 500 index level of 5,000, that represents approximately $250,000 of notional exposure for ES versus $25,000 for MES.

    That 10-to-1 relationship is the foundation for understanding Micro vs E-mini futures. But contract size is only part of the comparison. Tick value, margin, leverage, trading costs, liquidity, and position sizing also matter.

    Micro vs E-mini Futures: What’s the Difference?

    Micro E-mini futures are smaller-sized versions of major E-mini equity index futures. CME Group currently lists Micro E-mini contracts for major U.S. equity benchmarks including the S&P 500, Nasdaq-100, Dow Jones Industrial Average, and Russell 2000.

    The basic relationship looks like this:

    FeatureMicro E-mini FuturesE-mini Futures
    Contract sizeSmallerLarger
    Typical relationship1/10 of E-mini10× Micro
    Dollar exposure per pointLowerHigher
    Tick valueLowerHigher
    Position sizing flexibilityMore granularLess granular
    Margin requirementGenerally lower, but variesGenerally higher
    Market exposureSame underlying benchmarkSame underlying benchmark
    Main symbolsMES, MNQ, MYM, M2KES, NQ, YM, RTY

    CME describes Micro E-mini contracts as one-tenth the size of their E-mini counterparts. The smaller multiplier reduces the dollar value of each index movement while preserving exposure to the same benchmark.

    The 10:1 Contract-Size Relationship

    The simplest way to remember the difference is:

    10 Micro contracts ≈ 1 corresponding E-mini contract in notional exposure.

    For example:

    • 10 MES ≈ 1 ES
    • 10 MNQ ≈ 1 NQ
    • 10 MYM ≈ 1 YM
    • 10 M2K ≈ 1 RTY

    This relationship is about contract size and exposure. It does not mean that trading ten Micro contracts will have exactly the same total transaction costs or execution characteristics as trading one E-mini contract.

    What Stays the Same Between Micro and E-mini Futures?

    The Micro and E-mini versions generally track the same underlying equity indexes.

    That means the comparison is not primarily about choosing a different index. It is about choosing a different contract size for that index exposure.

    For example:

    • MES and ES track the S&P 500.
    • MNQ and NQ track the Nasdaq-100.
    • MYM and YM track the Dow Jones Industrial Average.
    • M2K and RTY track the Russell 2000.

    This makes Micro futures useful when a trader wants smaller increments of exposure rather than changing the underlying market.

    What Changes?

    The most important differences are:

    • Contract multiplier
    • Dollar value per index point
    • Dollar value per tick
    • Notional exposure
    • Margin requirements
    • Position-size flexibility
    • Trading-cost impact

    Understanding these differences is more useful than simply memorizing the names “Micro” and “E-mini.”

    Micro vs E-mini Futures Contract Sizes

    The contract multiplier determines how much a one-point movement in the underlying index is worth.

    CME’s current materials show the following relationships for the major U.S. equity-index contracts.

    IndexMicro SymbolMicro $/PointE-mini SymbolE-mini $/Point
    S&P 500MES$5ES$50
    Nasdaq-100MNQ$2NQ$20
    Dow Jones Industrial AverageMYM$0.50YM$5
    Russell 2000M2K$5RTY$50

    The exact notional value changes with the index level because futures exposure is calculated from the index price multiplied by the contract multiplier.

    S&P 500: MES vs ES

    The Micro E-mini S&P 500 contract is MES, while the larger E-mini S&P 500 contract is ES.

    CME specifies:

    • MES multiplier: $5 × S&P 500 Index
    • ES multiplier: $50 × S&P 500 Index

    At an index level of 5,000:

    MES:
    5,000 × $5 = $25,000

    ES:
    5,000 × $50 = $250,000

    So one ES contract represents ten times the notional exposure of one MES contract.

    Nasdaq-100: MNQ vs NQ

    For the Nasdaq-100:

    • MNQ uses a $2 multiplier.
    • NQ uses a $20 multiplier.

    Therefore, one NQ contract represents approximately ten times the notional exposure of one MNQ contract at the same index level.

    Because the Nasdaq-100 can make relatively large index moves, understanding this multiplier is particularly important when calculating potential profit and loss.

    Dow Jones: MYM vs YM

    The Micro E-mini Dow contract is MYM, while the E-mini Dow contract is YM.

    The multipliers are:

    • MYM: $0.50 per index point
    • YM: $5 per index point

    Again, the E-mini contract is ten times the size of the Micro version.

    Russell 2000: M2K vs RTY

    For the Russell 2000:

    • M2K: $5 per index point
    • RTY: $50 per index point

    CME identifies M2K as the smaller-sized version of the Russell 2000 E-mini contract and lists a minimum tick of 0.10 index points.

    Tick Size vs Tick Value: What’s the Difference?

    These two terms are easy to confuse.

    Tick Size

    👉Tick size is the smallest price increment by which a futures contract can move.

    Tick Value

    Tick value is the amount of money represented by that minimum price movement.

    The basic calculation is:

    Tick value = Tick size × Contract multiplier

    For MES, for example:

    0.25 index points × $5 = $1.25 per tick

    A one-point move contains four 0.25-point ticks, so:

    4 × $1.25 = $5 per point

    CME’s educational material confirms that a one-tick move in Micro E-mini S&P 500 futures is $1.25 and a one-point move is $5.

    Why Tick Value Matters

    Suppose MES moves 20 points.

    The calculation is:

    20 × $5 = $100

    For ES:

    20 × $50 = $1,000

    The underlying index moved the same number of points. The difference comes from the contract multiplier.

    That is why understanding the multiplier is essential before thinking about profit, loss or risk.

    How Much Does a Price Move Affect Your P&L?

    A simple formula helps:

    P&L = Number of Contracts × Point Movement × Dollar Value Per Point

    Consider a hypothetical 10-point move in the S&P 500.

    One MES Contract

    10 points × $5 = $50

    One ES Contract

    10 points × $50 = $500

    The calculation is hypothetical and excludes commissions, exchange fees, slippage and other trading costs.

    This also works in the opposite direction. A 10-point adverse move would represent the same dollar magnitude of loss before costs.

    That’s an important point: Micro futures are smaller, but they are not risk-free.

    Micro vs E-mini Futures Margin Requirements

    Margin is one of the most misunderstood parts of futures trading.

    Futures margin is not the same thing as paying the full notional value of a contract. Instead, a trader generally posts a performance bond or margin amount to establish a futures position.

    CME explains that the margin requirement is only a fraction of the contract’s total notional value.

    However, margin figures can change.

    They may differ according to:

    • Market conditions
    • Exchange requirements
    • Broker policies
    • Account type
    • Position type
    • Intraday versus overnight requirements

    CME’s published Micro E-mini margin information explicitly notes that margin estimates are subject to change.

    For that reason, a fixed dollar margin figure should not be treated as a permanent rule.

    Initial Margin vs Maintenance Margin

    Initial margin is generally the amount required to establish a futures position.

    Maintenance margin is the minimum account equity requirement that must generally be maintained while the position remains open.

    Exact requirements should always be checked with the relevant futures broker and exchange because they can change.

    Why Margin Shouldn’t Be Confused With Risk

    A common mistake is thinking:

    “If the broker lets me open the position with $X of margin, then $X is the amount I can safely risk.”

    That’s incorrect.

    Margin determines how much capital is required to carry a position under the applicable rules. Your actual market exposure can be much larger.

    CME illustrates this distinction by showing how a Micro E-mini S&P 500 contract can provide substantial notional exposure relative to the margin required.

    Micro vs E-mini Futures: Risk and Leverage

    Micro futures reduce the dollar amount attached to each index movement, but they do not remove leverage.

    That distinction matters.

    Suppose an index moves against a position by 50 points.

    For one MES:

    50 × $5 = $250

    For one ES:

    50 × $50 = $2,500

    The Micro contract creates a smaller dollar impact for the same index movement.

    This can also allow more granular position sizing. Instead of moving directly from one large contract to no position, a trader can potentially adjust exposure using smaller contracts.

    That flexibility does not eliminate the possibility of significant losses.

    Position Size Matters More Than the Contract Name

    The important question isn’t simply:

    “Are Micro futures safer?”

    A better question is:

    “How much dollar exposure does the position create relative to the account and risk plan?”

    Ten MES contracts have approximately the same contract-size exposure as one ES contract. Therefore, simply choosing Micro futures does not automatically create lower overall exposure if the number of contracts is increased.

    Liquidity and Trading Costs

    Micro and E-mini futures can differ in liquidity and trading costs, but those differences should be considered product by product rather than assumed universally.

    Liquidity can affect:

    • Bid-ask spreads
    • Order execution
    • Slippage
    • Ability to enter or exit larger positions
    • Transaction costs

    The E-mini contracts have historically been major equity-index futures products, while Micro contracts provide smaller versions of those exposures.

    A smaller contract does not automatically mean lower total trading cost.

    For example, if ten Micro contracts are required to replicate approximately one E-mini contract’s exposure, the commission structure may make the total cost different from trading one E-mini contract.

    Always check the current fee schedule for the broker and contract being considered.

    Micro vs E-mini Futures for Position Sizing

    One of the main practical differences is granularity.

    Suppose a hypothetical strategy calls for exposure equivalent to 0.3 of an ES contract.

    A trader cannot simply buy 0.3 of one standard ES futures contract.

    But the smaller Micro contract allows exposure to be built in smaller increments.

    For example:

    • 1 MES = 0.1 ES
    • 2 MES = 0.2 ES
    • 3 MES = 0.3 ES
    • 5 MES = 0.5 ES
    • 10 MES = approximately 1 ES

    This does not mean that every position should be constructed this way. It simply demonstrates why smaller contracts can provide more flexibility in position sizing.

    Are Micro Futures Less Risky Than E-mini Futures?

    One Micro contract has less dollar exposure than one corresponding E-mini contract.

    But that does not mean Micro futures are inherently low-risk.

    Risk depends on factors such as:

    • Number of contracts
    • Price movement
    • Position size
    • Account capital
    • Stop or exit methodology
    • Volatility
    • Trading costs
    • Leverage

    For example, ten MES contracts have approximately the same contract-size exposure as one ES contract.

    So the correct distinction is:

    Smaller contract ≠ automatically safer position.

    Instead:

    Smaller contract = smaller dollar exposure per contract.

    That difference is fundamental.

    Micro vs E-mini Futures: Liquidity, Fees and Execution

    When comparing the two contract sizes, look beyond the multiplier.

    Liquidity

    Liquidity describes how easily orders can be executed without significantly affecting the market price.

    The E-mini contracts have long been important benchmark futures products. Micro contracts provide smaller-sized access to the same underlying indexes.

    Actual liquidity can vary by product, contract month and market conditions.

    Commissions

    Commission structures vary by broker.

    Trading ten Micro contracts instead of one E-mini may produce a different total commission bill depending on the broker’s pricing model.

    This is why “Micro futures are cheaper” is too broad a statement.

    The contract itself has a smaller dollar value, but total trading cost depends on how many contracts you trade and what your broker charges.

    Slippage

    Slippage occurs when an order is executed at a different price from the one expected.

    It can be affected by:

    • Market volatility
    • Liquidity
    • Order type
    • Market conditions
    • Position size

    These factors should be considered separately from contract size.

    Futures Expiration and Settlement

    Micro and E-mini equity-index futures are not perpetual contracts.

    They have expiration cycles and settlement procedures.

    CME states that Micro E-mini equity-index futures follow the same general quarterly cycle as their corresponding E-mini products, with cash settlement procedures tied to the underlying indexes.

    Before expiration, a futures position can generally be:

    • Offset
    • Rolled into another contract month
    • Held through settlement where applicable

    CME specifically notes that traders should understand their approach to expiration and rollover before the contract reaches its final trading period.

    This is another reason to check the current contract specifications rather than relying on an old article.

    Micro vs E-mini Futures: Which One Fits a Given Situation?

    There isn’t one universally correct contract size for every trader.

    Instead, the comparison can be approached through the characteristics of each contract.

    Smaller exposure

    Micro contracts provide smaller dollar exposure per contract.

    More granular sizing

    Micro contracts allow exposure to be adjusted in smaller increments.

    Larger exposure per contract

    E-mini contracts produce a larger dollar change for every index-point movement.

    Scaling

    Micro contracts can provide more flexibility when building or reducing exposure in smaller increments.

    Transaction costs

    The number of contracts and broker fee structure should be considered before assuming one size is cheaper.

    The key is to compare exposure, position size, costs and risk together, rather than focusing on margin alone.

    Common Mistakes When Comparing Micro and E-mini Futures

    Mistake 1: Confusing Margin With Contract Value

    Margin is not the same as notional exposure.

    A relatively small margin requirement can control a much larger futures position.

    Mistake 2: Ignoring the Contract Multiplier

    Two contracts can track the same index but have very different dollar values per point.

    Always check the multiplier.

    Mistake 3: Assuming Ten Micros Cost the Same as One E-mini

    Ten Micro contracts approximate one E-mini in contract-size exposure, but fees and execution costs can differ.

    Mistake 4: Assuming Micro Means Low Risk

    A smaller contract reduces the dollar value per contract. It does not remove leverage or market risk.

    Mistake 5: Using Outdated Margin Figures

    Margin requirements change.

    CME’s own historical margin tables explicitly state that published estimates are subject to change.

    Mistake 6: Forgetting Expiration

    Futures have contract months and settlement procedures. A futures position should not be treated like a perpetual spot position.

    Micro vs E-mini Futures FAQs

    How many Micro futures equal one E-mini?

    For the major Micro E-mini equity-index contracts, 10 Micro contracts correspond approximately to one E-mini contract in contract size. For example, 10 MES contracts have approximately the same notional contract-size exposure as one ES contract.

    What is the difference between MES and ES?

    MES is the Micro E-mini S&P 500 futures contract, while ES is the larger E-mini S&P 500 futures contract. MES uses a $5 multiplier, while ES uses a $50 multiplier.

    What is the difference between MNQ and NQ?

    MNQ is the Micro E-mini Nasdaq-100 futures contract and NQ is the larger E-mini Nasdaq-100 contract. MNQ uses a $2 multiplier while NQ uses a $20 multiplier.

    Are Micro futures the same market as E-mini futures?

    The corresponding Micro and E-mini contracts provide exposure to the same underlying equity-index benchmark, but they have different contract multipliers and therefore different dollar exposure per point.

    Are Micro futures cheaper to trade?

    Not necessarily. A single Micro contract has smaller exposure, but traders may need multiple Micro contracts to replicate one E-mini contract. Total commissions and other trading costs depend on the number of contracts and the broker’s pricing.

    Are Micro futures less risky?

    One Micro contract has lower dollar exposure than one corresponding E-mini contract. However, total risk depends on the number of contracts, price movement, leverage, account size and other factors.

    What is the tick value of MES?

    MES has a minimum tick of 0.25 index points and a $5 multiplier, producing a tick value of $1.25.

    What is the tick value of ES?

    ES also moves in 0.25-point increments, but its $50 multiplier means each minimum tick is worth $12.50.

    What are the Micro futures symbols?

    CME identifies the major Micro E-mini equity-index symbols as:

    • MES — S&P 500
    • MNQ — Nasdaq-100
    • MYM — Dow Jones Industrial Average
    • M2K — Russell 2000

    Can Micro futures be used for smaller position sizing?

    Yes. Their smaller contract multipliers allow exposure to be adjusted in smaller increments than with the corresponding E-mini contracts. That can provide greater flexibility when managing position size.

    Do Micro and E-mini futures expire?

    Yes. Equity-index futures have contract months and expiration/settlement procedures. CME provides current contract calendars and settlement information, so traders should verify the applicable contract specifications before expiration.

    Key Takeaways

    The main difference between Micro and E-mini futures is contract size.

    Micro E-mini contracts are generally one-tenth the size of their corresponding E-mini contracts. That means:

    • MES is 1/10 the contract size of ES.
    • MNQ is 1/10 the contract size of NQ.
    • MYM is 1/10 the contract size of YM.
    • M2K is 1/10 the contract size of RTY.

    The smaller contract size produces a smaller dollar value per index point and allows more granular position sizing.

    But Micro futures still involve leverage, market risk, fees and expiration. A smaller contract should therefore be understood as a smaller unit of exposure, not as a risk-free or automatically safer trading product.

    For more market-focused educational resources, you can explore the OfferBin blog, while OfferBin.io provides live market data and token conversion tools for supported crypto assets. OfferBin itself is a market-data reference and converter, not a futures broker or trading platform.

  • What Is a Brokerage Account? How It Works, Types & Fees

    What Is a Brokerage Account? How It Works, Types & Fees

    A brokerage account is an investment account that lets you buy and sell securities such as stocks, bonds, exchange-traded funds (ETFs), and mutual funds through a brokerage firm. Unlike a bank account, which is mainly designed for deposits and payments, a brokerage account is designed to hold investments and cash used for investing.

    In simple terms, think of a brokerage account as a home for your investments. You deposit money into the account, use that money to purchase investments, and the brokerage keeps a record of what you own. When you sell an investment, the proceeds generally return to the account as cash.

    This guide explains what a brokerage account is, how brokerage accounts work, the main types, fees, taxes, risks, and how beginners can open and use one.

    What Is a Brokerage Account?

    A brokerage account is an investment account held with a brokerage firm that allows you to buy and sell financial securities.

    Depending on the brokerage and account, you may be able to invest in:

    • Stocks
    • Bonds
    • ETFs
    • Mutual funds
    • Options
    • Other securities and investment products

    The exact investments available vary by brokerage firm and account type. Investor.gov defines a brokerage account as an investment account at a registered brokerage firm that allows investors to buy and sell products such as stocks, bonds, mutual funds, and ETFs.

    The simplest way to understand it

    A brokerage account is not the investment itself.

    For example:

    • Brokerage account: The account where your investments and available cash are held.
    • Stock: An investment you can purchase through the account.
    • ETF: Another investment you can purchase through the account.
    • Broker: The intermediary that provides access to the market and executes orders.
    • Portfolio: The collection of investments you hold.

    So if you deposit $5,000 into a brokerage account and use $2,000 to purchase an ETF, the brokerage account is the container holding your cash and investment position.


    How Does a Brokerage Account Work?

    The basic process is straightforward:

    1. You open an account with a brokerage firm.
    2. You provide the required information and verify your identity.
    3. You deposit money.
    4. You choose an investment.
    5. You submit a buy order.
    6. The broker processes the transaction.
    7. The investment appears in your account.
    8. You can monitor, hold, or eventually sell the investment.

    A simple example

    Suppose you open a brokerage account and deposit $1,000.

    You decide to invest $600 in an ETF and leave $400 as cash.

    Your account might then show:

    HoldingAmount
    ETF$600
    Available cash$400
    Total account value$1,000

    If the ETF rises in value, your investment becomes worth more. If it falls, its value decreases.

    The brokerage account itself does not guarantee that your investments will increase. Investment values can rise or fall based on market conditions.

    Brokerage firms act as intermediaries between investors and financial markets, helping customers place orders to buy and sell investments.


    What Is a Brokerage Account Used For?

    People use brokerage accounts for several investing purposes.

    Buying and selling investments

    The most basic use is buying and selling securities such as stocks, bonds, ETFs, and mutual funds.

    Building an investment portfolio

    You can hold multiple investments in one account to create a portfolio.

    For example, a portfolio could contain:

    • U.S. stocks
    • International stocks
    • Bond funds
    • ETFs
    • Cash

    The actual combination depends on the investor’s goals, time horizon, risk tolerance, and investment strategy.

    Investing for long-term goals

    A taxable brokerage account can provide flexibility for goals that do not fit neatly inside a retirement account.

    Some investors use brokerage accounts alongside retirement accounts rather than as a replacement for them.

    Holding investments

    A brokerage account also provides a place to keep investments after you purchase them.

    You can generally view:

    • Current holdings
    • Account balance
    • Cash balance
    • Investment values
    • Transaction history
    • Gains and losses

    What Can You Buy With a Brokerage Account?

    The available investments depend on the brokerage firm, but common choices include:

    InvestmentWhat it represents
    StocksOwnership interests in companies
    BondsDebt issued by governments or organizations
    ETFsFunds that trade on an exchange
    Mutual fundsPooled investments managed according to a stated strategy
    OptionsContracts tied to an underlying security or asset
    CashUninvested money held in the account

    Not every brokerage offers every product.

    For example, one brokerage may provide stocks, ETFs, and mutual funds while another may offer a much broader selection of securities and trading tools.

    If you’re learning about different asset classes, understanding how digital assets differ from traditional securities is also useful. OfferBin’s educational coverage includes an explanation of how cryptocurrency differs from traditional investments, although OfferBin itself is not a brokerage or exchange.


    Types of Brokerage Accounts

    There are several ways brokerage accounts can be classified.

    The most important distinction for beginners is usually cash vs. margin.

    Other classifications include individual vs. joint ownership and self-directed vs. managed accounts.


    Cash Brokerage Account

    A cash account requires you to pay the full amount for securities you purchase rather than borrowing money from the brokerage.

    For example, if you have $2,000 available and purchase $1,500 of investments, you are using your own available funds.

    Investor.gov defines a cash account as a brokerage account in which the investor must pay the full amount for securities purchased and cannot borrow from the broker to fund those purchases.

    Why cash accounts matter

    A cash account is simpler because you are not borrowing money from the brokerage.

    However, cash accounts still have trading rules. For example, U.S. securities transactions are subject to settlement and other regulatory requirements, and certain trading activity in cash accounts can result in restrictions. The SEC updated its investor bulletin on cash-account trading in August 2026.


    Margin Brokerage Account

    A margin account allows a brokerage firm to lend money to an investor to purchase securities, using securities in the account as collateral.

    For example, suppose you have $5,000 in an account and a brokerage allows you to borrow additional money.

    You could potentially purchase more securities than you could with your cash alone.

    But borrowing creates additional risk.

    You may have to:

    • Pay interest on borrowed money
    • Maintain required account equity
    • Deposit additional cash or securities if the account falls below requirements
    • Potentially have securities sold by the brokerage to cover a shortfall

    Investor.gov warns that margin trading can result in larger losses and that a brokerage may sell securities to address a margin deficiency.

    Cash account vs. margin account

    FeatureCash AccountMargin Account
    Uses your own fundsYesYes
    Borrowing from brokerNoYes
    Interest on borrowed moneyNoPossible
    Purchasing powerLimited to available fundsCan be increased through borrowing
    RiskInvestment riskInvestment + borrowing risk
    Beginner complexityLowerHigher

    When opening an account, pay attention to the account type you are selecting. The SEC specifically warns that some brokerage applications may make margin the default option, so investors should confirm which type they are opening.


    Individual Brokerage Account

    An individual brokerage account has one account owner.

    The account holder generally controls the investments and transactions.

    This is one of the most common structures for personal investing.


    Joint Brokerage Account

    A joint brokerage account has multiple owners.

    It may be used by spouses, partners, or other eligible individuals, depending on the brokerage and applicable rules.

    Ownership, withdrawal rights, taxes, and other details can vary, so the account agreement matters.


    Self-Directed Brokerage Account

    With a self-directed account, you generally decide what investments to buy and sell.

    The brokerage provides the platform, account infrastructure, market access, and order execution, while you make the investment decisions.

    This can provide greater control, but it also means you are responsible for researching investments and understanding the risks.


    Managed Brokerage Account

    A managed brokerage account may involve a financial professional or automated investment service managing investments according to an agreed approach.

    A robo-advisor, for example, may use software to construct and manage a portfolio based on information supplied by the customer.

    The services, fees, investment choices, and management arrangements vary between providers.


    How Much Does a Brokerage Account Cost?

    Opening a brokerage account may cost nothing at some firms, but that does not mean investing is completely free.

    Potential costs can include:

    • Trading commissions
    • Account maintenance fees
    • Transfer fees
    • Wire fees
    • Margin interest
    • Fund expense ratios
    • Options contract fees
    • Other transaction-related costs

    The exact fee structure depends on the brokerage and products you use.

    Some online brokers advertise commission-free trading for certain products, but investors should still review the complete fee schedule.

    Why fees matter

    Suppose two investments have similar performance before costs.

    If one carries higher ongoing costs, those costs can reduce the amount of money that remains invested.

    This is why comparing the complete fee structure is more useful than looking only at a headline such as “$0 commission.”


    Are Brokerage Accounts Taxable?

    Whether and how a brokerage account is taxed depends on the account type, investments, transactions, and your tax jurisdiction.

    For a typical taxable brokerage account in the United States, investment income can include items such as:

    • Capital gains
    • Dividends
    • Interest

    The IRS lists capital gains, interest, and dividends among types of investment income that may be taxable.

    Example

    Suppose you buy shares for $2,000 and later sell them for $2,500.

    The $500 difference may represent a capital gain for tax purposes, subject to applicable rules and circumstances.

    Tax treatment can become more complicated depending on:

    • How long you held the investment
    • Your tax status
    • The type of investment
    • Whether losses offset gains
    • Your country or state
    • Applicable tax laws

    Because tax rules change and vary by jurisdiction, investors should consult current tax guidance or a qualified tax professional for their own situation.


    Brokerage Account vs. Bank Account

    A brokerage account and a bank account serve different primary purposes.

    FeatureBrokerage AccountBank Account
    Main purposeInvestingSaving, payments, and cash management
    StocksUsually availableGenerally not held directly
    ETFsUsually availableGenerally not held directly
    BondsOften availableGenerally not held directly
    Investment riskYesDepends on the product
    Investment gains/lossesPossibleUsually not the main purpose
    Payment servicesLimited/variesCommon
    Deposit insuranceDepends on structure and jurisdictionDepends on bank and applicable insurance

    A bank account is generally designed around cash deposits and payments, while a brokerage account is designed around investments.

    The two can work together.

    For example:

    Bank account → transfer money → brokerage account → purchase investments


    Brokerage Account vs. Retirement Account

    A brokerage account is also different from a retirement account such as an IRA or 401(k).

    The exact rules depend on the jurisdiction and account type, but U.S. retirement accounts generally have specific tax rules and contribution restrictions that do not apply in the same way to ordinary taxable brokerage accounts.

    FeatureTaxable BrokerageRetirement Account
    Main purposeGeneral investingRetirement savings
    Investment choicesOften broadDepends on plan/provider
    Tax treatmentGenerally taxableSpecial tax treatment
    Contribution rulesGenerally no annual federal contribution limit like an IRAContribution rules may apply
    Withdrawal rulesGenerally flexibleSpecial rules may apply
    Employer contributionNoSome employer plans may offer matching

    A brokerage account can therefore complement retirement savings rather than necessarily replacing a retirement account.


    Is a Brokerage Account Safe?

    There are two separate questions here:

    1. Is the account protected if the brokerage fails?
    2. Can investments inside the account lose money?

    Those are not the same thing.

    In the United States, eligible customers of SIPC-member brokerage firms may receive protection when a brokerage firm fails and customer assets are missing, subject to applicable limits. SIPC protection is generally up to $500,000 per customer, including a $250,000 limit for cash claims. It does not protect you from normal investment losses caused by market prices falling.

    Important distinction

    If you buy a stock for $1,000 and it falls to $700, that is a market loss.

    SIPC protection is not designed to reimburse you simply because the stock declined.

    That distinction is essential when evaluating brokerage-account safety.


    How to Open a Brokerage Account

    Opening a brokerage account generally involves several steps.

    Choose a brokerage firm

    Compare factors such as:

    • Fees
    • Available investments
    • Account types
    • Trading tools
    • Customer support
    • Educational resources
    • Minimums
    • Regulatory information
    • Cash-management options

    Complete the application

    Depending on the jurisdiction and brokerage, you may need to provide information such as:

    • Full name
    • Address
    • Identification information
    • Employment information
    • Financial information
    • Investment experience

    The specific requirements vary.

    Select the account type

    You may need to choose between:

    • Cash
    • Margin
    • Individual
    • Joint
    • Managed
    • Self-directed

    Do not select margin simply because it is presented as an option. Understand how borrowing works before enabling it.

    Fund the account

    You can generally transfer money from an eligible bank account or another permitted funding source.

    The available methods depend on the brokerage.

    Choose your investments

    Once the account is funded, you can research investments available through that brokerage and place orders according to your own strategy.

    Opening the account does not automatically mean your money is invested. Funding an account and investing the money are separate steps.


    How to Use a Brokerage Account as a Beginner

    If you are new to investing, focus first on understanding how the account works.

    Understand what you own

    Know the difference between:

    • Cash
    • Individual stocks
    • Bonds
    • ETFs
    • Mutual funds
    • Other securities

    Learn basic order types

    Two common order types are:

    Market order: An instruction to buy or sell at the best available price under the order’s conditions.

    Limit order: An instruction to buy or sell only at a specified price or better.

    The availability and mechanics of order types can vary between brokerages and securities.

    Understand diversification

    Putting all of your money into one investment exposes the portfolio to the risks of that investment.

    Diversification spreads exposure across different investments or asset categories, although diversification cannot eliminate investment losses.

    Understand your fees

    Review both obvious and less-obvious costs.

    A brokerage with no trading commission can still have other fees or costs associated with certain services or investments.

    Be careful with margin

    Borrowing can increase purchasing power, but it can also increase losses and introduce interest costs and margin requirements.


    Can You Withdraw Money From a Brokerage Account?

    Generally, you can withdraw available cash from a brokerage account, subject to the brokerage’s policies and any applicable restrictions.

    But there is an important distinction between cash available to withdraw and money invested in securities.

    If your money is invested, you may need to sell the investment first.

    For example:

    Investment → sell → proceeds become available cash → withdraw

    Selling an investment can have tax consequences in some jurisdictions.

    There can also be settlement-related timing before sale proceeds become fully available, depending on the security and applicable market rules.


    How Does a Brokerage Account Make Money?

    A brokerage firm may generate revenue in several ways depending on its business model.

    Potential sources include:

    • Commissions
    • Account fees
    • Interest on margin loans
    • Interest earned on certain customer cash arrangements
    • Fees for specific services
    • Fund or product-related revenue
    • Other permitted business activities

    Not every brokerage uses the same model.

    This is why reading the firm’s fee schedule and disclosures is more useful than assuming that a “commission-free” account has no costs.


    What Are the Benefits of a Brokerage Account?

    Common benefits include:

    • Access to a broad range of investments
    • Flexible withdrawals
    • Ability to build a diversified portfolio
    • Access to online investing tools
    • No annual contribution limit comparable to an IRA in a standard U.S. taxable account
    • Ability to invest for goals outside retirement
    • Choice between self-directed and managed approaches, depending on the provider

    The specific benefits depend on the brokerage, account structure, investments, and jurisdiction.


    What Are the Disadvantages of a Brokerage Account?

    A brokerage account also has limitations and risks.

    Market losses

    Investments can lose value.

    Taxes

    Taxable investment income and realized gains may create tax obligations.

    Fees

    Certain services and investments can involve costs.

    Complexity

    Some investments and trading features can be difficult for beginners to understand.

    Margin risk

    Borrowing can increase both purchasing power and potential losses.

    Emotional decision-making

    Markets can move quickly, and reacting impulsively to short-term price changes can affect investment decisions.

    A brokerage account provides access to markets; it does not remove investment risk.


    Common Brokerage Account Mistakes

    Confusing the account with the investment

    A brokerage account is the account structure. A stock, ETF, or bond is an investment held through that account.

    Choosing margin without understanding it

    Margin introduces borrowing, interest, collateral requirements, and additional risk.

    Looking only at commissions

    A $0 commission does not necessarily mean $0 total cost.

    Ignoring taxes

    Selling investments for a gain or receiving dividends or interest can have tax implications.

    Investing before understanding the product

    Before buying an investment, understand what it is, how it works, and what could cause its value to rise or fall.

    Assuming protection means guaranteed returns

    Investor protection mechanisms and investment performance are separate issues.


    Brokerage Account FAQ

    What is a brokerage account in simple words?

    A brokerage account is an investment account that lets you buy, sell, and hold investments such as stocks, bonds, ETFs, and mutual funds through a brokerage firm.

    How does a brokerage account work?

    You deposit money into the account, use available funds to purchase investments, and the brokerage records and maintains your positions. When you sell an investment, the proceeds generally return to the account as cash.

    Can beginners open a brokerage account?

    Yes. Many brokerage firms offer accounts designed for individual investors, including beginners. The eligibility requirements and available products vary by provider and jurisdiction.

    How much money do you need to open a brokerage account?

    There is no single minimum that applies to every brokerage. Some firms may allow accounts with no minimum deposit, while others may impose account or product-specific requirements.

    What can you buy with a brokerage account?

    Depending on the brokerage, you may be able to buy stocks, bonds, ETFs, mutual funds, options, and other securities.

    Is a brokerage account the same as a bank account?

    No. A bank account is primarily designed for cash deposits, payments, and banking services, while a brokerage account is designed for buying, selling, and holding investments.

    Do you pay taxes on a brokerage account?

    Tax treatment depends on the account, investment, transaction, and jurisdiction. In the U.S., taxable investment accounts can generate taxable capital gains, dividends, and interest.

    Can you withdraw money from a brokerage account?

    Generally, yes, if the money is available for withdrawal. If your money is invested, you may need to sell the investment first, and selling can have tax consequences.

    What is the difference between a cash account and a margin account?

    A cash account requires you to pay the full amount for securities you purchase. A margin account allows you to borrow from the brokerage to purchase securities, which introduces interest costs and additional risk.

    Is a brokerage account safe?

    A brokerage account can have investor-protection mechanisms depending on the country, brokerage, and account structure. In the U.S., eligible customers of SIPC-member firms may receive protection against certain losses caused by brokerage failure, but SIPC does not protect against normal market losses.

    Can you have more than one brokerage account?

    Yes, investors can have multiple brokerage accounts when permitted by the providers and applicable rules. Different accounts may be used for different investment goals, providers, or strategies.

    Is a brokerage account good for investing?

    A brokerage account provides access to investments, but whether it fits a particular investor depends on factors such as goals, time horizon, risk tolerance, tax situation, and available alternatives.


    Brokerage Account: Key Takeaways

    A brokerage account is essentially an investment account that provides access to financial markets.

    The most important points to remember are:

    • A brokerage account is different from an individual investment.
    • You can use it to buy and sell securities.
    • Stocks, bonds, ETFs, and mutual funds are common investments.
    • Cash and margin accounts work differently.
    • Margin involves borrowing and additional risk.
    • Brokerage fees vary between firms and products.
    • Tax treatment depends on the account, investment, transaction, and jurisdiction.
    • Investor protection does not eliminate market risk.
    • You can generally withdraw available cash, but selling investments first may be necessary.
    • Opening a brokerage account and actually investing the money are two separate steps.

    For readers who also follow digital assets, it is important to keep another distinction clear: a brokerage account is not the same thing as a crypto exchange account or crypto wallet. OfferBin itself is a live crypto price tracker and token converter, not a crypto exchange or brokerage; its converter is for reference and does not move or store funds.

    For more educational market and digital-asset resources, you can explore OfferBin’s market guides and use its live data tools to check current crypto prices and token conversions.


    Sources & Further Reading

    For financial definitions and regulatory information, useful primary sources include:

    These sources are particularly useful because brokerage rules, tax treatment, settlement requirements, and investor-protection rules can change over time.

  • Best Futures to Trade in 2026: Top Contracts Compared

    Best Futures to Trade in 2026: Top Contracts Compared

    If you’re looking for the best futures to trade in 2026, start with one important point: there is no single futures contract that is best for every trader.

    The right market depends on liquidity, volatility, contract size, tick value, trading hours, strategy, and how much risk you can realistically manage. Popular choices include S&P 500 futures (ES/MES), Nasdaq-100 futures (NQ/MNQ), crude oil (CL/MCL), gold (GC/MGC), Russell 2000 futures, Dow futures, and 10-Year Treasury futures.

    For many traders, the most useful starting point is a highly liquid market with a contract size that matches their risk plan. Smaller contracts can also provide more precise position sizing. CME’s E-nano equity-index futures, launched in August 2026, add another smaller-sized option for four major U.S. equity benchmarks.

    Quick answer: The best futures to research in 2026 include ES/MES, NQ/MNQ, CL/MCL, GC/MGC, RTY/M2K, YM/MYM, and ZN. Instead of choosing solely by popularity, compare liquidity, volatility, tick value, contract size, trading session, and your maximum acceptable risk.

    Best Futures to Trade in 2026 at a Glance

    Futures marketCommon contractsMain exposureOften useful forKey consideration
    S&P 500ES / MESU.S. large-cap stocksDay trading, index exposureHighly liquid, but still leveraged
    Nasdaq-100NQ / MNQU.S. technology-heavy equitiesMomentum and active tradingCan experience larger price swings
    Russell 2000RTY / M2KU.S. small-cap stocksIndex diversification, momentumCan behave differently from large-cap indexes
    Dow JonesYM / MYM30 large U.S. companiesIndex tradingDifferent composition and movement profile
    WTI Crude OilCL / MCLEnergyCommodity trading, macro/newsCan move sharply around energy events
    GoldGC / MGCPrecious metalsMacro and metals exposureSensitive to rates, dollar and geopolitical conditions
    10-Year TreasuryZNU.S. interest ratesRates and macro tradingRequires understanding bond-price/yield relationships
    E-nano indexesNES / NNQ / N2K / NDOWMajor U.S. indexesSmaller-scale equity-index exposureNewer products with smaller multipliers

    The table is a starting point, not a ranking. Contract specifications, liquidity and market conditions can change, so traders should verify current specifications before placing trades.

    What Makes a Futures Contract Good to Trade?

    A futures contract becomes attractive for different reasons depending on the trader. Popularity alone is not enough.

    Five characteristics matter particularly:

    1. Liquidity
    2. Volatility
    3. Contract size
    4. Tick value
    5. Execution conditions

    CME explains that traders can evaluate futures liquidity using measures such as trading volume, open interest, bid/offer spreads and order-book depth.

    Liquidity

    Liquidity describes how easily you can enter or exit a position without causing a large price impact.

    Highly liquid futures markets generally offer:

    • More active participation
    • More trading volume
    • Tighter bid-ask spreads
    • Greater market depth
    • Potentially less slippage under normal conditions

    However, liquidity can change during different trading sessions and around major economic announcements.

    Trading Volume

    Volume measures how many contracts change hands during a specified period.

    High volume can indicate active participation, but volume alone does not tell you everything about execution quality. You should also consider the spread and available depth near the current price.

    Open Interest

    Open interest represents outstanding futures positions that remain open.

    It is different from daily trading volume. Volume measures contracts traded during a period, while open interest reflects contracts that remain open.

    Bid-Ask Spread

    The bid is the highest displayed price buyers are offering, while the ask is the lowest displayed price sellers are requesting.

    A smaller spread can reduce one component of transaction cost, although commissions, exchange fees and slippage also matter.

    Market Depth

    Market depth shows the quantity of orders available at different price levels.

    A market can have high volume but still behave differently during a major news event when liquidity conditions change rapidly.


    How Does Volatility Affect Futures Trading?

    Volatility describes how much and how quickly a market’s price moves.

    High volatility can create more trading opportunities, but it also increases the potential size of losses.

    This distinction is especially important with futures because leverage means a relatively small amount of posted margin can control a much larger notional position.

    The CFTC warns that leverage can amplify both gains and losses and that futures traders can be required to add funds when positions move against them.

    High-volatility futures

    Markets such as Nasdaq-100 futures and crude oil futures can experience significant intraday movement.

    That can appeal to momentum or short-term traders, but larger movements also require careful position sizing.

    Lower-volatility does not mean low risk

    A market with smaller average price movements can still create substantial losses if the contract is too large for the account.

    The important question is not:

    “Which futures market moves the most?”

    It is:

    “Which contract’s normal movement can I manage within my risk plan?”


    Best Equity Index Futures to Trade in 2026

    Equity index futures are among the most widely followed futures markets because they provide exposure to major stock-market benchmarks.

    The main contracts worth understanding are ES, NQ, RTY and YM, along with their smaller-sized alternatives.

    S&P 500 Futures: ES and MES

    E-mini S&P 500 futures (ES) track the S&P 500 index and use a $50 multiplier. A 0.25-point minimum tick therefore represents $12.50 per contract.

    Micro E-mini S&P 500 futures (MES) use a smaller multiplier of $5.

    That makes MES useful when a trader wants exposure to the same benchmark with a smaller contract size.

    Why traders watch ES

    ES can be attractive for traders who want:

    • Broad U.S. large-cap equity exposure
    • A heavily followed benchmark
    • Active intraday markets
    • A market connected to major U.S. economic events

    ES vs MES

    FeatureESMES
    UnderlyingS&P 500S&P 500
    Multiplier$50$5
    Relative size1x1/10 ES
    Tick size0.25 index point0.25 index point
    Tick value$12.50$1.25
    Main benefitLarger exposureSmaller exposure

    The smaller contract does not remove market risk. It simply reduces the dollar impact of each index movement.


    Nasdaq-100 Futures: NQ and MNQ

    E-mini Nasdaq-100 futures (NQ) provide exposure to the Nasdaq-100.

    NQ uses a $20 multiplier, while Micro E-mini Nasdaq-100 futures (MNQ) use a $2 multiplier.

    Why traders watch NQ

    Nasdaq-100 futures are closely associated with large technology and growth-oriented companies.

    They can be relevant for traders focused on:

    • Momentum
    • Technology-related market moves
    • U.S. equity indexes
    • Intraday price movement

    But greater movement can also mean greater risk.

    NQ vs MNQ

    FeatureNQMNQ
    UnderlyingNasdaq-100Nasdaq-100
    Multiplier$20$2
    Relative size1x1/10 NQ
    Primary advantageLarger exposureSmaller exposure

    For traders comparing NQ and MNQ, contract size should be one of the first considerations.


    Russell 2000 Futures: RTY and M2K

    Russell 2000 futures provide exposure to a U.S. small-cap equity benchmark.

    The standard contract is RTY, while Micro E-mini Russell 2000 futures (M2K) provide a smaller contract size.

    Russell futures can behave differently from large-cap indexes because smaller companies may respond differently to changes in interest rates, domestic economic expectations and market sentiment.

    They can therefore be useful for traders who specifically want small-cap exposure rather than simply another version of the S&P 500.


    Dow Futures: YM and MYM

    E-mini Dow futures (YM) provide exposure to the Dow Jones Industrial Average.

    The Micro E-mini Dow contract, MYM, provides a smaller contract size.

    Dow futures can appeal to traders who want an equity-index market with a different composition from the S&P 500 and Nasdaq-100.

    The key point is not that YM is inherently better or worse than ES or NQ. Its usefulness depends on the exposure and price behavior you’re looking for.


    Best Commodity Futures to Trade in 2026

    Commodity futures can behave differently from equity indexes because supply, demand, weather, inventories, geopolitical events and macroeconomic conditions can have a direct impact on prices.

    Two major markets to understand are crude oil and gold.

    Crude Oil Futures: CL and MCL

    WTI crude oil futures (CL) represent 1,000 barrels, with a minimum tick of $0.01 per barrel and a $10 tick value.

    Micro WTI crude oil futures (MCL) represent 100 barrels and have a $1 tick value.

    Why crude oil attracts traders

    WTI is influenced by factors including:

    • OPEC decisions
    • Inventory data
    • Energy demand
    • Geopolitical events
    • Global economic conditions
    • Production expectations

    CME notes that WTI traders commonly watch the EIA Weekly Petroleum Status Report and OPEC developments.

    CL vs MCL

    FeatureCLMCL
    Contract size1,000 barrels100 barrels
    Tick size$0.01$0.01
    Tick value$10$1
    Relative size1x1/10 CL
    Main differenceLarger exposureSmaller exposure

    Crude oil can move quickly around scheduled reports and unexpected geopolitical developments, so a smaller contract does not automatically make the market easy.


    Gold Futures: GC and MGC

    Gold futures (GC) represent 100 troy ounces, with a minimum price fluctuation of $0.10 per ounce, equivalent to $10 per tick. Micro Gold futures (MGC) represent 10 troy ounces and have a $1 tick value.

    Gold prices can respond to:

    • Interest-rate expectations
    • Inflation expectations
    • U.S. dollar movements
    • Geopolitical uncertainty
    • Central-bank policy
    • Global economic conditions

    CME describes GC as a major gold futures market and notes its relationship with broader macroeconomic factors.

    GC vs MGC

    FeatureGCMGC
    Contract size100 troy oz.10 troy oz.
    Tick size$0.10/oz.$0.10/oz.
    Tick value$10$1
    Relative size1x1/10 GC

    Gold can look familiar because it is widely discussed in financial news, but familiarity does not eliminate futures leverage risk.


    10-Year Treasury Futures: ZN

    10-Year U.S. Treasury Note futures (ZN) are used to trade exposure to the U.S. Treasury market and interest-rate expectations.

    CME lists ZN with a $100,000 face amount at maturity and provides electronic trading access through CME Globex.

    Treasury futures are different from equity and commodity futures because their price behavior is closely connected to:

    • Interest-rate expectations
    • Federal Reserve policy
    • Inflation data
    • Employment data
    • Economic growth expectations
    • Demand for government securities

    For traders who understand fixed-income markets, ZN can be an important futures market. For beginners who do not understand the price-yield relationship, it may require more study before trading.


    Micro Futures vs E-mini Futures vs E-nano Futures

    One of the most important developments for futures traders in 2026 is the expansion of smaller-sized equity-index contracts.

    CME launched its E-nano equity-index futures on August 24, 2026, covering the S&P 500, Nasdaq-100, Russell 2000 and Dow Jones Industrial Average.

    What Are Micro Futures?

    Micro E-mini contracts are generally one-tenth the size of their corresponding E-mini equity-index contracts.

    For example:

    • ES → MES
    • NQ → MNQ
    • RTY → M2K
    • YM → MYM

    This smaller contract size can make position sizing more flexible.

    What Are E-nano Futures?

    E-nano equity-index futures are another step down in contract size.

    CME says the E-nano multiplier is one-tenth the size of the corresponding Micro E-mini and one-hundredth the size of the E-mini.

    IndexE-miniMicro E-miniE-nano
    S&P 500$50 multiplier$5$0.50
    Nasdaq-100$20$2$0.20
    Russell 2000$50$5$0.50
    Dow Jones$5$0.50$0.05

    CME’s E-nano specifications currently include product codes NES, NNQ, N2K and NDOW.

    Why contract size matters

    Suppose the S&P 500 moves 10 index points.

    Ignoring fees and execution differences:

    • ES: 10 × $50 = $500
    • MES: 10 × $5 = $50
    • E-nano S&P 500: 10 × $0.50 = $5

    This illustrates why contract selection matters so much.

    The smaller contract is not automatically “safer.” It simply changes the dollar value of price movements.


    Best Futures for Beginners

    There is no universally easiest futures contract.

    For beginners, a useful selection framework is:

    • Understandable underlying market
    • Strong liquidity
    • Clear contract specifications
    • Manageable tick value
    • Contract size that fits the risk plan
    • Trading hours that match your schedule
    • A strategy that has been tested before using meaningful capital

    Micro and E-nano contracts can provide smaller notional exposure in some equity-index markets, but beginners still need to understand margin, leverage, expiration, settlement and position sizing.

    The CFTC describes futures trading as volatile and complex and warns that individuals can lose all of their money and, in some situations, more than the amount initially deposited.

    If you are comparing futures with crypto markets, you can also review OfferBin’s educational discussion of cryptocurrency investing before treating the two markets as interchangeable. OfferBin’s cryptocurrency investment guide


    Best Futures for Day Trading

    Day traders often prioritize liquidity, predictable execution, active trading sessions and enough movement to make their strategy viable.

    Markets commonly researched for day trading include:

    ES/MES

    Useful for broad U.S. equity exposure and active index trading.

    NQ/MNQ

    Often considered by traders who specifically want Nasdaq-100 exposure and larger intraday movement.

    CL/MCL

    Relevant for traders who specialize in energy markets and understand crude-oil catalysts.

    GC/MGC

    Useful for traders who follow precious metals and macroeconomic events.

    RTY/M2K

    Provides small-cap equity exposure and can behave differently from the major large-cap indexes.

    The important distinction is that best for day trading does not mean most volatile.

    A market can move rapidly but still be a poor fit if its movement is too large for your position size or strategy.


    Best Futures for Scalping

    Scalping places even greater emphasis on execution.

    Important factors include:

    • Bid-ask spread
    • Market depth
    • Volume
    • Short-term volatility
    • Commission costs
    • Slippage
    • Trading-session liquidity

    A contract with frequent price movement may look attractive, but if execution costs are high relative to the expected move, the strategy can become less efficient.

    This is why liquidity should be evaluated alongside volatility rather than separately.


    Best Futures for Momentum Trading

    Momentum traders generally look for markets where price can sustain directional movement.

    Potential markets to research include:

    • NQ/MNQ
    • ES/MES
    • CL/MCL
    • GC/MGC
    • RTY/M2K

    But momentum is a strategy, not a property that makes a contract universally superior.

    A trader should examine how the market behaves around the specific session, news calendar and strategy rules being used.


    Best Futures for Trend Following

    Trend-following strategies can be applied across several futures markets.

    Equity indexes, commodities, currencies and interest-rate futures can all produce trends at different times.

    The contract itself is only one part of the decision.

    A trend-following trader should also consider:

    • Time frame
    • Average price movement
    • Trading costs
    • Contract liquidity
    • Roll schedule
    • Position sizing
    • Maximum drawdown
    • Stop-loss distance

    How Much Money Do You Need to Trade Futures?

    There is no single dollar amount that works for everyone.

    That’s because margin is not the same thing as the amount of money you should risk.

    CFTC explains that futures margin is a performance bond rather than a conventional down payment, and that futures positions are marked to market.

    A broker may also impose requirements above exchange minimums.

    Contract value vs margin

    A futures contract can have a large notional value while requiring only a fraction of that amount as margin.

    That creates leverage.

    For example, an equity-index contract’s notional value can be calculated using:

    Futures price × contract multiplier = notional value

    CME uses this formula for equity-index futures.

    But the amount of margin required to hold a position is not the same as the amount you can afford to lose.

    A better question

    Instead of asking:

    “What is the minimum account size?”

    ask:

    “What contract size allows my planned stop distance and risk per trade to stay within my risk limits?”

    That is a much more useful risk-management question.


    Futures Tick Value Explained

    A tick is the minimum price fluctuation defined by the exchange.

    CME notes that tick sizes vary by futures contract. For example, the E-mini S&P 500 moves in 0.25-point increments, while each tick is worth $12.50 because of its $50 multiplier.

    A simple formula is:

    Dollar move = Number of ticks × Tick value × Number of contracts

    For example, if a contract has a $1 tick value and moves 20 ticks:

    20 × $1 = $20

    This simple calculation is essential before entering any futures position.


    How to Choose the Best Futures Contract

    Instead of choosing a contract because someone calls it “the best,” use this process.

    Start with your strategy

    Are you:

    • Day trading?
    • Scalping?
    • Swing trading?
    • Trend following?
    • Trading macroeconomic events?
    • Trading commodity-specific news?

    Your strategy should narrow the market choices.

    Check liquidity

    Look at:

    • Volume
    • Open interest
    • Bid-ask spread
    • Market depth
    • Typical session activity

    CME specifically identifies these as useful liquidity considerations.

    Check volatility

    Ask:

    • How much does the market normally move?
    • How quickly can it move?
    • Does the movement fit your stop?
    • Can your account handle the dollar impact?

    Check tick value

    Never enter a futures market without knowing how much each minimum price movement is worth.

    Check contract size

    Compare:

    • Standard
    • E-mini
    • Micro
    • E-nano where available

    Check trading hours

    A market can behave differently during:

    • U.S. open
    • European session
    • Asian session
    • Economic releases
    • Major market overlaps

    Check your risk per trade

    Your position size should be determined by your risk framework, not by the maximum number of contracts your broker allows.


    👉 ES vs NQ: Which Futures Market Should You Research?

    ES and NQ are both major equity-index futures, but they represent different benchmarks.

    ES

    Tracks the S&P 500 and provides broad large-cap U.S. equity exposure.

    NQ

    Tracks the Nasdaq-100 and provides exposure to a more technology- and growth-oriented index.

    The practical difference

    If your strategy is sensitive to volatility, the difference in price behavior matters more than the names of the indexes.

    Instead of asking:

    “Is ES better than NQ?”

    ask:

    “Which market’s typical movement and tick value fit my strategy and risk limits?”

    That question produces a more useful answer.


    ES vs MES

    The underlying benchmark is the same, but the contract multiplier is different.

    ES uses a $50 multiplier while MES uses $5.

    That means MES provides a smaller dollar exposure per index point.

    For traders who need finer position sizing, that difference can be significant.


    NQ vs MNQ

    The same principle applies.

    NQ uses a $20 multiplier, while MNQ uses $2.

    The choice is therefore not simply about which market is more popular.

    It’s about:

    • exposure
    • tick value
    • position size
    • risk per trade
    • strategy
    • execution

    Most Liquid Futures Contracts

    Liquidity changes over time and varies by contract month and trading session, so a static list of “the most liquid futures” should not be treated as permanent.

    Major contracts commonly associated with deep futures markets include:

    • S&P 500 futures
    • Nasdaq-100 futures
    • WTI crude oil
    • Gold
    • U.S. Treasury futures
    • Major currency futures

    CME’s liquidity framework emphasizes more than volume alone. Traders should also consider open interest, spreads and order-book depth.

    Before trading, check current market data rather than relying on an old liquidity ranking.


    Most Volatile Futures

    Volatility changes with market conditions.

    Potentially fast-moving markets can include:

    • Nasdaq-100 futures
    • Crude oil futures
    • Gold futures
    • Russell 2000 futures
    • Other commodity and equity-index contracts during major events

    But “most volatile” does not mean “best.”

    High volatility can produce larger opportunities and larger losses.

    For a trader with a small risk limit, a smaller contract in a highly active market may be more practical than a larger contract in the same market.


    Common Futures Trading Mistakes

    Choosing a contract because it is popular

    Popularity doesn’t automatically make a contract appropriate for your strategy.

    Confusing margin with affordable risk

    The margin requirement tells you what is required to maintain the position under applicable rules. It does not tell you what you should risk.

    Ignoring tick value

    A seemingly small price movement can translate into a meaningful dollar gain or loss.

    Trading excessive volatility

    Fast markets can punish oversized positions quickly.

    Ignoring liquidity

    A market may look attractive on a chart but behave differently when liquidity becomes thinner.

    Failing to check contract specifications

    Every futures contract has its own specifications, including contract size, tick size, expiration and settlement characteristics. CME emphasizes that these specifications directly affect trading decisions.

    Treating futures like stocks

    Futures are leveraged derivatives with contract specifications, expiration schedules and margin requirements.

    The CFTC advises traders to understand the specific obligations and risks before trading.


    Futures Trading Risk: What You Should Know

    Futures trading can create substantial losses because leverage magnifies the financial impact of price movements.

    The CFTC specifically warns that futures trading is volatile and complex and that losses can exceed the initial amount deposited in some circumstances.

    Before trading, understand:

    • Initial margin
    • Maintenance margin
    • Variation margin
    • Contract value
    • Tick value
    • Expiration
    • Settlement
    • Position size
    • Stop-loss risk
    • Slippage
    • Commissions and fees

    Never use emergency savings, money needed for living expenses or other funds you cannot afford to lose as trading capital. CFTC guidance emphasizes using only risk capital for speculative trading.


    Frequently Asked Questions

    What are the best futures to trade in 2026?

    Common futures markets to research in 2026 include ES/MES, NQ/MNQ, CL/MCL, GC/MGC, RTY/M2K, YM/MYM and ZN. The appropriate contract depends on liquidity, volatility, contract size, tick value, trading strategy and risk tolerance.

    What is the best futures contract to trade?

    There is no universal best futures contract. ES, NQ, crude oil, gold and Treasury futures serve different purposes and have different contract specifications and risk profiles.

    What are the most liquid futures contracts?

    Major equity indexes, crude oil, gold, Treasury and currency futures are among the major liquid futures markets. However, liquidity varies by contract, expiration month and trading session, so current volume, open interest, spread and market depth should be checked.

    What futures are best for day trading?

    ES/MES and NQ/MNQ are commonly researched for equity-index day trading. CL/MCL and GC/MGC may also suit traders who specialize in energy or metals. The right choice depends on strategy, execution conditions and risk limits.

    What are the best futures for beginners?

    Beginners should generally focus on understanding contract specifications, liquidity, tick value, margin and risk before selecting a market. Smaller contracts such as Micro and, where appropriate, E-nano contracts can provide smaller exposure, but they do not remove leverage risk.

    Are Micro futures good for beginners?

    Micro futures can make position sizing more flexible because their contract multipliers are smaller than corresponding E-mini contracts. However, they are still leveraged futures and require the same understanding of margin, expiration, execution and risk.

    What is the difference between ES and MES?

    Both track the S&P 500. ES has a $50 multiplier, while MES has a $5 multiplier, making MES one-tenth the size of ES by multiplier.

    What is the difference between NQ and MNQ?

    Both track the Nasdaq-100. NQ uses a $20 multiplier while MNQ uses a $2 multiplier.

    What futures have the most volatility?

    Volatility changes over time. Nasdaq-100, crude oil, gold and small-cap equity futures can experience substantial price movement, especially around major economic or market events. Higher volatility also increases potential risk.

    How much money do you need to trade futures?

    There is no universal amount. Exchange and broker margin requirements differ, and the appropriate account size depends on contract size, strategy and risk management. Margin should not be confused with the amount you can afford to lose.

    What makes a good futures contract?

    A useful futures contract for a particular trader may combine adequate liquidity, suitable volatility, manageable tick value, appropriate contract size, reliable execution and trading hours that fit the strategy.

    How does futures liquidity affect trading?

    Higher liquidity can support tighter spreads and deeper markets, but liquidity is not constant. Traders should consider volume, open interest, bid-ask spread and order-book depth rather than relying on one metric.

    How does volatility affect futures trading?

    Volatility determines how quickly and how far prices can move. Higher volatility can create more opportunity but also increases the potential dollar impact of a position, especially when leverage is involved.


    Final Takeaway

    The best futures to trade in 2026 are not necessarily the contracts with the biggest price movements or the most attention online.

    A better approach is to compare:

    Liquidity → Volatility → Contract Size → Tick Value → Trading Session → Strategy → Risk

    For equity-index traders, ES/MES and NQ/MNQ are important markets to understand. For commodities, CL/MCL and GC/MGC offer major energy and precious-metals exposure. RTY/M2K and YM/MYM provide alternative equity-index exposure, while ZN gives traders access to the U.S. Treasury market.

    The biggest 2026 development for smaller-sized equity-index exposure is the arrival of CME’s E-nano futures. These contracts are one-tenth the size of Micro E-minis, creating another contract-size option for the S&P 500, Nasdaq-100, Russell 2000 and Dow Jones benchmarks.

    The key is to choose the contract that fits your strategy and risk framework, rather than assuming one market is objectively best for everyone.

    For readers who also follow cryptocurrency markets, OfferBin provides live crypto market information and token-conversion tools alongside its educational resources. Explore OfferBin’s market resources

  • Student Loan Plans UK: Plan 1, 2, 4, 5 & Postgraduate Explained

    Student Loan Plans UK: Plan 1, 2, 4, 5 & Postgraduate Explained

    If you have a UK student loan, the amount you repay depends mainly on which student loan plan you have and how much you earn.

    For the 2026/27 tax year, there are five main undergraduate repayment plans — Plan 1, Plan 2, Plan 4 and Plan 5 — plus the separate Postgraduate Loan repayment plan. Plans have different income thresholds, interest rules and write-off periods.

    The most important point is that your student loan balance does not determine how much you repay each year. Repayments are based on your income above the threshold for your plan.

    Student Loan Plans at a Glance

    Here are the main repayment thresholds and rates for 2026/27:

    Student loan plan2026/27 annual thresholdMonthly thresholdRepayment rate
    Plan 1£26,900£2,2419%
    Plan 2£29,385£2,4489%
    Plan 4£33,795£2,8169%
    Plan 5£25,000£2,0839%
    Postgraduate Loan£21,000£1,7506%

    These are the official 2026/27 thresholds. Your repayment is calculated on the portion of income above the relevant threshold, not on your entire salary.

    For example, if you are on Plan 2 and earn £40,000:

    • Annual income: £40,000
    • Plan 2 threshold: £29,385
    • Income above threshold: £10,615
    • Repayment: 9% × £10,615
    • Annual repayment: £955.35
    • Average monthly equivalent: about £79.61

    Your actual deductions can vary depending on how you are paid and how payroll calculations are applied.

    What Are Student Loan Plans?

    Student loan plans are different sets of repayment rules that determine when you repay your loan, how much you repay and how interest is applied.

    Your plan is generally determined by factors such as:

    • Where you studied
    • When you started your course
    • Whether the loan was undergraduate or postgraduate
    • Which UK student-finance system provided the loan

    The main UK income-contingent plans are:

    • Plan 1
    • Plan 2
    • Plan 4
    • Plan 5
    • Postgraduate Loan

    Plan 1 generally covers older loans, including borrowers who started certain courses before September 2012 and borrowers in Northern Ireland. .Plan 4 applies to eligible Scottish borrowers. Plan 2 covers many English and Welsh undergraduate borrowers who started under the previous system, while Plan 5 applies to new English undergraduate borrowers from August 2023.

    👉Plan 1 Student Loans

    Plan 1 applies mainly to borrowers who started eligible undergraduate courses before September 2012. It also covers certain borrowers in Northern Ireland.

    For 2026/27:

    • Threshold: £26,900 a year
    • Monthly threshold: about £2,241
    • Repayment rate: 9% above the threshold
    • Current interest rate: 4.1%

    The Plan 1 interest rate is subject to the applicable rules and can be linked to RPI or the Bank of England base rate plus 1%, whichever is lower under the relevant rules. For 1 September 2026 to 31 August 2027, the maximum applicable Plan 1 rate is 4.1%.

    How Plan 1 repayment works

    Suppose you earn £33,000 a year.

    Your income above the annual threshold is:

    £33,000 − £26,900 = £6,100

    You repay 9% of that amount:

    £6,100 × 9% = £549 a year

    That is approximately £45.75 a month when expressed as an annual average.

    Plan 2 Student Loans

    Plan 2 is commonly associated with English undergraduate courses that started between September 2012 and July 2023 and Welsh undergraduate borrowers who started from September 2012.

    For 2026/27:

    • Threshold: £29,385 a year
    • Monthly threshold: about £2,448
    • Repayment rate: 9% above the threshold
    • Interest can vary according to income
    • Current Plan 2 interest is subject to a 6% cap for the 2026/27 period

    GOV.UK states that after study, Plan 2 interest is normally RPI plus up to 3%, depending on income, with the current 6% cap applying during the relevant 2026/27 period.

    Plan 2 repayment example

    Imagine your annual salary is £50,000.

    Income above the threshold:

    £50,000 − £29,385 = £20,615

    Repayment:

    £20,615 × 9% = £1,855.35 a year

    That is approximately £154.61 per month when divided by 12.

    Notice that the calculation is based on the £20,615 above the threshold, not the full £50,000 salary.

    Plan 4 Student Loans

    Plan 4 applies primarily to eligible Scottish student-loan borrowers.

    For 2026/27:

    • Threshold: £33,795 a year
    • Monthly threshold: about £2,816
    • Repayment rate: 9% above the threshold
    • Current interest rate: 4.1%

    Plan 4 example

    If you earn £36,000:

    £36,000 − £33,795 = £2,205

    Your annual repayment is:

    £2,205 × 9% = £198.45

    That works out at about £16.54 per month on an annual-average basis.

    Plan 5 Student Loans

    Plan 5 is the newer undergraduate repayment plan for eligible English students who started courses from August 2023.

    For 2026/27:

    • Threshold: £25,000 a year
    • Monthly threshold: about £2,083
    • Repayment rate: 9%
    • Interest is normally linked to RPI
    • Repayment term: 40 years

    The government introduced Plan 5 for new English undergraduate borrowers from the 2023/24 academic year.

    Plan 5 example

    If you earn £30,000:

    £30,000 − £25,000 = £5,000

    Your annual repayment would be:

    £5,000 × 9% = £450

    That is approximately £37.50 per month on an annual-average basis.

    Postgraduate Loan Repayment Plan

    A Postgraduate Loan is separate from the undergraduate plans.

    For 2026/27:

    • Threshold: £21,000 a year
    • Monthly threshold: £1,750
    • Repayment rate: 6%
    • Write-off period for eligible England and Wales postgraduate loans: 30 years

    Interest is normally RPI plus 3%, with a 6% cap applying between 1 September 2026 and 31 August 2027.

    Postgraduate Loan example

    Suppose you earn £30,000.

    Income above the £21,000 threshold:

    £30,000 − £21,000 = £9,000

    Repayment:

    £9,000 × 6% = £540 a year

    That is equivalent to approximately £45 per month.

    Which Student Loan Plan Am I On?

    If you are unsure which plan you have, do not guess based only on your current salary.

    Your plan can depend on your:

    1. Country or region of study
    2. Course start date
    3. Type of course
    4. Type of student finance
    5. Previous loans

    A useful starting point is your Student Loans Company information and your payroll records.

    Your employer’s payroll process can also use your student-loan plan information when calculating deductions. HMRC’s 2026/27 payroll guidance specifically lists Plan 1, Plan 2, Plan 4, Plan 5 and Postgraduate Loans.

    If you have paperwork that uses different terminology, look for the plan type rather than assuming that every student loan follows the same repayment rules.

    How Do Student Loan Repayments Work?

    The basic calculation is straightforward:

    Repayment = (Income − Plan Threshold) × Repayment Rate

    But only apply the formula when your income is above the applicable threshold.

    For example, a Plan 2 borrower earning £40,000 in 2026/27 would have:

    £40,000 − £29,385 = £10,615

    Then:

    £10,615 × 9% = £955.35

    So the annual repayment is approximately £955.35.

    Your outstanding student loan balance does not change that annual repayment calculation. The balance and interest affect how long the loan may remain outstanding, but the repayment amount is primarily linked to income.

    What Happens If Your Income Changes?

    Student loan repayments are income-contingent, so your deductions can change when your earnings change.

    Income can include things such as:

    • Salary
    • Bonuses
    • Overtime
    • Other earnings included under the applicable repayment rules

    If your income temporarily rises above the threshold, you may make repayments during that period.

    GOV.UK also explains that if your annual income ends up below your plan’s annual threshold, you may be able to request a refund of certain repayments made during the year.

    Student Loan Interest Rates in 2026/27

    Interest is separate from your repayment calculation.

    This distinction is important:

    Your repayment is based on income.

    Interest affects your outstanding balance.

    For 2026/27, GOV.UK lists:

    PlanCurrent 2026/27 interest position
    Plan 14.1% maximum applicable rate for 1 Sept 2026–31 Aug 2027
    Plan 2Variable according to income, with a 6% cap during the relevant 2026/27 period
    Plan 44.1%
    Plan 5Normally RPI
    Postgraduate LoanNormally RPI + 3%, with a 6% cap during the relevant 2026/27 period

    Interest can continue to be applied even when you are below the repayment threshold. This is why the amount shown on your student-loan statement can behave differently from the amount being deducted from your payslip.

    When Are Student Loans Written Off?

    A student loan is not necessarily repaid like a conventional personal loan.

    If you do not repay the full balance within the applicable repayment period, the remaining amount can be cancelled under the rules for your plan.

    The timing depends on your plan and circumstances.

    PlanGeneral cancellation period
    Older Plan 1 loansDepends on when the loan was taken out; some older loans have age-based rules
    Plan 1 loans taken out from Sept 2006 to before Sept 201225 years after the April when repayments were first due
    Plan 230 years after the April when repayments were first due
    Plan 540 years after the April when repayments were first due
    Postgraduate Loan30 years after the April when repayments were first due

    The exact cancellation rules can depend on the type and date of the loan, so use your official loan information rather than assuming a single write-off period applies to everyone.

    Plan 1 vs Plan 2 vs Plan 4 vs Plan 5

    The biggest differences are the threshold, repayment rate, interest rules and repayment term.

    FeaturePlan 1Plan 2Plan 4Plan 5
    2026/27 threshold£26,900£29,385£33,795£25,000
    Repayment rate9%9%9%9%
    Main associationOlder UK loansMany 2012–2023 English/Welsh borrowersScottish borrowersNewer English undergraduate borrowers
    Interest4.1% current rateVariable, capped at 6% currently4.1%Normally RPI
    General repayment termDepends on loan date30 yearsDepends on loan date/rules40 years

    The table is a simplified overview. Your exact eligibility and terms depend on the loan you actually took out.

    What If You Have More Than One Student Loan?

    Some borrowers have more than one type of student loan.

    For example, you may have an undergraduate loan and a separate Postgraduate Loan.

    In that situation, deductions can apply under the rules for both loan types.

    For 2026/27, undergraduate Plan 1, 2, 4 and 5 repayments use a 9% rate above the relevant threshold, while the Postgraduate Loan uses a 6% rate above its threshold.

    GOV.UK provides specific rules for borrowers with multiple plan types, including how repayments are allocated when someone has more than one undergraduate plan.

    This is one reason a simple “student loan percentage” does not always tell the whole story.

    How Much Will You Repay on Different Salaries?

    Here are simplified annual examples for 2026/27.

    Annual incomePlan 1Plan 2Plan 4Plan 5Postgraduate Loan
    £25,000£0£0£0£0£240
    £30,000£279£55£0£450£540
    £40,000£1,179£955£559£1,350£1,140
    £50,000£2,079£1,855£1,459£2,250£1,740

    These examples use the annual thresholds and repayment percentages published for 2026/27. Actual payroll deductions can differ slightly because PAYE uses pay-period thresholds and payroll calculations.

    Do Student Loans Affect Your Credit Score?

    Student loan repayments are not treated like ordinary commercial borrowing for UK credit reporting.

    GOV.UK states that student loans do not appear on credit reports and do not affect your credit score. However, lenders may consider your student-loan repayment when assessing affordability for other borrowing, such as a mortgage.

    So a student loan can matter to your disposable income and affordability assessment even though it is not reported in the same way as a conventional credit balance.

    Can You Pay Off a Student Loan Early?

    Yes. GOV.UK states that there is no penalty for making voluntary early repayments.

    Whether making additional payments is appropriate depends on your circumstances, including:

    • Your plan
    • Your income
    • Your outstanding balance
    • Expected future earnings
    • Interest rates
    • How long you expect to remain in repayment
    • Your other financial priorities

    Because these factors vary substantially between borrowers, there is no single repayment strategy that applies to everyone.

    Student Loan Plans for People Living Overseas

    Moving outside the UK does not automatically remove your repayment obligations.

    The Student Loans Company publishes country-specific overseas earnings thresholds and repayment information. These can differ from the UK thresholds.

    For example, GOV.UK publishes separate 2026/27 overseas thresholds for Plan 1, Plan 2, Plan 5 and Postgraduate Loans.

    If you live abroad, check the official SLC information for the country where you live rather than applying the UK PAYE threshold directly.

    Common Student Loan Plan Questions

    What is the student loan threshold for 2026/27?

    For 2026/27, the annual thresholds are £26,900 for Plan 1, £29,385 for Plan 2, £33,795 for Plan 4, £25,000 for Plan 5 and £21,000 for Postgraduate Loans.

    What percentage do I repay?

    Plans 1, 2, 4 and 5 use a 9% repayment rate on income above the relevant threshold. Postgraduate Loans use 6%.

    Is Plan 5 the same as Plan 2?

    No. Plan 5 has a lower 2026/27 repayment threshold of £25,000 compared with £29,385 for Plan 2. Plan 5 also has a 40-year repayment term and normally applies RPI-only interest, while Plan 2 has different interest rules and a 30-year repayment period.

    What student loan plan am I on?

    Your plan normally depends on where and when you studied and the type of loan you received. Your Student Loans Company information and repayment records are the safest places to confirm your plan.

    Do I repay my student loan if I earn below the threshold?

    Normally, you do not make income-based repayments when your earnings are below the applicable threshold. However, interest can still be applied to your outstanding balance.

    Does my student loan balance determine my monthly payment?

    No. For income-contingent repayments, the amount you owe does not determine the amount you repay each year. Your income and repayment-plan threshold are the key factors.

    When does a student loan get written off?

    The period depends on the plan. Plan 2 loans generally have a 30-year cancellation period, Plan 5 has a 40-year period, and Postgraduate Loans in England and Wales generally have a 30-year period. Some older Plan 1 loans have different rules.

    Can I have an undergraduate loan and a Postgraduate Loan?

    Yes. A borrower can have an undergraduate student loan and a separate Postgraduate Loan, with repayments calculated under the relevant rules for each type.

    Key Takeaways

    Student loan plans can look complicated because the rules depend on when and where you studied, but the basic repayment system is relatively simple.

    For 2026/27:

    • Plan 1: £26,900 threshold and 9% repayment
    • Plan 2: £29,385 threshold and 9% repayment
    • Plan 4: £33,795 threshold and 9% repayment
    • Plan 5: £25,000 threshold and 9% repayment
    • Postgraduate Loan: £21,000 threshold and 6% repayment

    The amount you owe is not what determines your annual income-based repayment. Instead, you generally repay a percentage of income above your plan’s threshold.

    Because thresholds, interest rates and repayment rules can change, check the latest official information before making decisions about your student loan.

    For additional online guides and resources, you can also explore Offerbin.io.

    Official Sources

  • Multiple Jobs PAYE Student Loan Calculator UK: 2026/27 Guide

    Multiple Jobs PAYE Student Loan Calculator UK: 2026/27 Guide

    If you have two or more jobs, working out your UK student loan repayment can be confusing. The key point is that PAYE student loan deductions are normally calculated separately for each employment, rather than by simply adding all your salaries together.

    For the 2026/27 tax year, the repayment threshold depends on your student loan plan. Plan 1, Plan 2, Plan 4 and Plan 5 repayments are generally charged at 9% of earnings above the relevant threshold, while a Postgraduate Loan is charged at 6% above its threshold.

    This guide explains how student loan repayments work with multiple PAYE jobs, how to estimate your deductions, what happens with a second job, and how Self Assessment can change the calculation.

    How Student Loan Repayments Work With Multiple Jobs

    If you have more than one employer, each employer normally looks at the pay from that employment when deciding whether a student loan deduction is due.

    That means your employers do not normally combine your salaries for ordinary PAYE student loan deductions.

    For example, suppose you have a Plan 2 student loan and receive:

    JobMonthly Pay
    Job 1£2,500
    Job 2£500
    Total£3,000

    For 2026/27, the Plan 2 monthly threshold is £2,448.75.

    Job 1 is above the threshold, so that employment can generate a student loan deduction. Job 2 is below the threshold, so it does not generate a Plan 2 deduction through that employment.

    The important point is that the £3,000 combined monthly income is not simply compared with the £2,448.75 threshold for ordinary PAYE deductions.

    Multiple Jobs PAYE Student Loan Calculator: The Basic Method

    To estimate a PAYE student loan deduction for each job, you need:

    • Your student loan plan
    • Your pay before deductions
    • How often you are paid
    • The applicable repayment threshold
    • Whether you also have a Postgraduate Loan

    For a standard student loan plan, the basic calculation is:

    PAYE student loan repayment = (pay above the applicable threshold) × 9%

    For a Postgraduate Loan:

    Postgraduate Loan repayment = (pay above the threshold) × 6%

    The calculation is normally performed for the relevant pay period by payroll.

    Example: Monthly Plan 2 Salary

    Suppose you earn £3,000 per month from one PAYE job and have a Plan 2 loan.

    The 2026/27 monthly Plan 2 threshold is £2,448.75.

    £3,000 − £2,448.75 = £551.25

    9% of £551.25 = £49.61

    So the estimated Plan 2 student loan deduction is about £49.61 for that monthly pay period, before considering any other payroll-specific circumstances.

    2026/27 Student Loan Repayment Thresholds

    The following thresholds apply from 6 April 2026 to 5 April 2027.

    Loan PlanAnnual ThresholdMonthly ThresholdWeekly ThresholdRepayment Rate
    Plan 1£26,900£2,241.66£517.309%
    Plan 2£29,385£2,448.75£565.099%
    Plan 4£33,795£2,816.25£649.909%
    Plan 5£25,000£2,083.33£480.769%
    Postgraduate Loan£21,000£1,750£403.846%

    These are the 2026/27 employer payroll thresholds published by HMRC.

    The threshold is important because you do not repay 9% of your entire salary. The 9% applies to the earnings above the relevant threshold for Plans 1, 2, 4 and 5.

    Do You Pay Student Loan Repayments on a Second Job?

    You may pay student loan repayments on a second job, but only if the pay from that employment is above the applicable repayment threshold.

    For ordinary PAYE deductions, the salaries from your different jobs are not simply combined to determine whether each employer should make a deduction.

    For example, with a Plan 1 loan:

    JobMonthly PayAbove £2,241.66?PAYE Student Loan Deduction
    Job 1£1,500No£0
    Job 2£1,000No£0

    Although the combined income is £2,500 per month, neither employment individually exceeds the monthly Plan 1 threshold.

    This is one of the biggest sources of confusion for people with multiple jobs.

    How Is Student Loan Calculated With Two Jobs?

    The calculation depends on each employment’s pay.

    Consider a Plan 2 borrower with:

    • Job 1: £2,700 per month
    • Job 2: £1,200 per month

    The 2026/27 Plan 2 monthly threshold is £2,448.75.

    Job 1

    £2,700 − £2,448.75 = £251.25

    £251.25 × 9% = £22.61

    Job 2

    £1,200 is below £2,448.75.

    Student loan deduction = £0

    Estimated total PAYE deduction

    £22.61 + £0 = £22.61

    The important thing is that Job 2 does not become subject to the Plan 2 deduction simply because your combined income is above the threshold.

    What If Both Jobs Are Above the Threshold?

    Suppose you have a Plan 2 loan and receive:

    • Job 1: £3,000 per month
    • Job 2: £2,800 per month

    Both jobs are above the 2026/27 monthly Plan 2 threshold of £2,448.75.

    Job 1

    £3,000 − £2,448.75 = £551.25

    9% = £49.61

    Job 2

    £2,800 − £2,448.75 = £351.25

    9% = £31.61

    Combined estimated PAYE deductions

    £49.61 + £31.61 = £81.22

    So having two jobs can result in student loan deductions from both employments when each employment individually exceeds the relevant threshold.

    What If Both Jobs Are Below the Threshold?

    This is where multiple-job calculations can look surprising.

    Imagine you have a Plan 2 loan:

    • Job 1 = £2,000 per month
    • Job 2 = £1,500 per month

    Combined pay = £3,500 per month.

    However, each employment is below the 2026/27 Plan 2 monthly threshold of £2,448.75.

    Under ordinary PAYE treatment, neither job would generate a Plan 2 student loan deduction for that monthly pay period.

    That does not mean your total annual income is irrelevant in every possible situation. Self Assessment and other circumstances can produce a different calculation.

    How Does PAYE Work With Multiple Jobs?

    PAYE is operated through payroll by your employers.

    For student loan deductions, payroll uses the relevant repayment plan and pay period to determine whether a deduction is required.

    Your employer’s payroll system can calculate the student loan and postgraduate loan deductions based on the applicable thresholds.

    This is why your payslip can show a student loan deduction even though your total annual salary calculation may look different.

    Student loan repayments taken through employment are based on individual pay periods. If you are paid monthly, the payroll calculation is made each month.

    Same Employer vs Different Employers

    Having two jobs does not necessarily mean you have two completely separate financial situations for every purpose. However, for ordinary PAYE student loan deductions, each employment is treated according to the payroll rules that apply to it.

    Two jobs with different employers

    Each employer operates its own payroll.

    For example:

    EmploymentMonthly PayPlan 2 ThresholdDeduction
    Employer A£2,600£2,448.75Yes
    Employer B£1,400£2,448.75No

    Employer A may deduct a Plan 2 repayment, while Employer B does not.

    Multiple jobs with the same employer

    The payroll setup can differ depending on how the employments are recorded and processed. If you are unsure why your deduction differs from an estimate, check your payslip and speak with your employer’s payroll team.

    Do not assume that simply adding two salary figures gives you the PAYE student loan deduction.

    Does a Second Job Increase Student Loan Repayments?

    It can, but not necessarily through PAYE in the way you might expect.

    If the second employment itself is above the relevant threshold, that job can produce an additional PAYE student loan deduction.

    If the second employment remains below the threshold, it may produce no PAYE student loan deduction even when your combined earnings are high.

    Your overall repayment position can also depend on whether you are required to complete a Self Assessment tax return.

    Student Loan Repayment With Two Jobs and Self Assessment

    Self Assessment is an important exception to the simple PAYE example.

    If you are self-employed or complete a Self Assessment tax return for another reason, HMRC can calculate your student loan repayment based on your income for the year.

    If you are both employed and self-employed, your combined income can therefore become relevant to the annual calculation.

    This is different from simply asking:

    “Should my second PAYE employer deduct student loan repayments?”

    Those are two different questions.

    For Self Assessment, the calculation is based on the relevant annual income, and repayments already made through PAYE can be taken into account.

    If you are unsure whether you need to complete Self Assessment or how your student loan should be handled, use the current GOV.UK guidance or speak to HMRC/a qualified tax professional.

    What Happens If You Have a Postgraduate Loan Too?

    A Postgraduate Loan is treated separately from the standard undergraduate student loan repayment.

    For 2026/27:

    • Postgraduate Loan threshold: £21,000 per year
    • Monthly threshold: £1,750
    • Weekly threshold: £403.84
    • Repayment rate: 6%

    You can have an undergraduate student loan and a Postgraduate Loan at the same time.

    For example, if you earn £2,500 in a month and have both a Plan 2 loan and a Postgraduate Loan:

    Postgraduate Loan

    £2,500 − £1,750 = £750

    6% × £750 = £45

    Plan 2

    £2,500 − £2,448.75 = £51.25

    9% × £51.25 = £4.61

    Estimated combined deduction

    £45 + £4.61 = £49.61

    Payroll rules determine how these deductions are applied.

    How Much Student Loan Will I Repay With Two Jobs?

    There is no single answer without knowing:

    • your student loan plan
    • pay from Job 1
    • pay from Job 2
    • pay frequency
    • whether you have a Postgraduate Loan
    • whether you are also subject to Self Assessment
    • the applicable tax year

    A simple PAYE estimate can be made job by job.

    Example

    Plan 1 borrower:

    • Job 1 = £2,500/month
    • Job 2 = £1,500/month

    Plan 1 monthly threshold for 2026/27 = £2,241.66.

    Job 1:

    £2,500 − £2,241.66 = £258.34

    9% = £23.25

    Job 2:

    £1,500 is below the threshold.

    Deduction = £0

    Estimated combined PAYE student loan deduction = £23.25.

    This is an illustration, not a replacement for an official payroll calculation.

    Student Loan Deductions From Multiple Jobs: Common Mistakes

    Mistake 1: Adding all salaries before applying the PAYE threshold

    This can produce the wrong answer for ordinary multiple-employer PAYE calculations.

    Mistake 2: Using last year’s threshold

    Student loan thresholds can change between tax years.

    For 2026/27, Plan 2 is £29,385 annually, compared with £28,470 in 2025/26.

    Mistake 3: Forgetting the loan plan

    Plan 1, Plan 2, Plan 4 and Plan 5 have different thresholds.

    Mistake 4: Forgetting a Postgraduate Loan

    A Postgraduate Loan has a separate threshold and 6% repayment rate.

    Mistake 5: Assuming PAYE and Self Assessment work identically

    They do not. PAYE deductions are based on employment pay periods, while Self Assessment can calculate repayment using annual income.

    Mistake 6: Treating an estimate as an official payroll result

    A calculator can help you understand the numbers, but your employer’s payroll system determines the actual PAYE deduction.

    How to Check Your Student Loan Deduction

    If the amount on your payslip does not match your expectation, check:

    1. Your student loan plan.
    2. Your gross pay for that pay period.
    3. How often you are paid.
    4. Whether a Postgraduate Loan is also recorded.
    5. Whether the deduction is shown separately on your payslip.
    6. Whether you recently changed jobs.
    7. Whether your employer has received the correct student loan information.

    If deductions appear to be missing or incorrect, contact your employer’s payroll team and, where appropriate, Student Loans Company or HMRC.

    Frequently Asked Questions

    Do you pay student loan repayments on a second job?

    You may. Under ordinary PAYE rules, a student loan deduction can apply to a second employment when the pay from that employment is above the relevant repayment threshold. The income from separate jobs is not simply combined for the purpose of deciding whether each PAYE employer should make a deduction.

    Are student loan repayments calculated separately for each job?

    For PAYE employment, deductions are normally based on the pay from each employment and its relevant pay period. This means two salaries are not simply added together before applying the PAYE threshold.

    Do both employers deduct student loan repayments?

    They can. If the earnings from both employments are above the applicable threshold for the loan plan, both employers may make student loan deductions through payroll.

    Can having two jobs increase student loan repayments?

    Yes. If your second employment is itself above the applicable threshold, it can create an additional PAYE student loan deduction. Your repayment position may also differ if you complete Self Assessment.

    What happens if both jobs are below the student loan threshold?

    For ordinary PAYE deductions, neither employment would normally generate a student loan deduction for that pay period if both are below the applicable threshold.

    How does PAYE work with multiple jobs?

    Each employer runs its own PAYE payroll. For student loan deductions, the employer considers the relevant pay and repayment plan for that employment rather than simply combining all of your salaries.

    How much student loan will I repay with two jobs?

    It depends on your loan plan, income from each job, pay frequency and whether you also have a Postgraduate Loan or Self Assessment obligations. Calculate each PAYE employment using the applicable threshold and repayment rate.

    Does a second job affect student loan repayments?

    It can. A second job can result in another PAYE deduction if the pay from that employment exceeds the applicable threshold. However, simply having combined income above the threshold does not automatically mean every job produces a deduction.

    What are the 2026/27 student loan thresholds?

    For 2026/27, the annual thresholds are £26,900 for Plan 1, £29,385 for Plan 2, £33,795 for Plan 4, £25,000 for Plan 5 and £21,000 for a Postgraduate Loan.

    What if I have a student loan and a Postgraduate Loan?

    You can have both. The undergraduate plan uses a 9% repayment rate above its relevant threshold, while the Postgraduate Loan uses a 6% rate above £21,000 annually for 2026/27.

    Does Self Assessment change the calculation?

    It can. HMRC calculates student loan repayments through Self Assessment using the relevant annual income. If you are employed as well as self-employed, your combined income can be relevant to the annual calculation, with qualifying PAYE repayments taken into account.

    Final Takeaway

    If you have multiple PAYE jobs, do not assume that your employers simply add your salaries together before calculating student loan deductions.

    For ordinary PAYE repayments, the relevant threshold is applied to the pay from each employment. A second job can therefore produce an additional deduction if its pay is above the threshold, while a job below the threshold may produce no PAYE student loan deduction.

    For 2026/27, Plan 1, Plan 2, Plan 4 and Plan 5 repayments are generally charged at 9% above their respective thresholds, while Postgraduate Loans use a 6% rate above the £21,000 threshold.

    If you also complete Self Assessment, the calculation can be different because annual income becomes relevant.

    Always check the current GOV.UK guidance for your circumstances, particularly when changing jobs, holding multiple loan types or completing a Self Assessment tax return.

    Sources: GOV.UK — HMRC rates and thresholds for employers 2026/27; GOV.UK — student loan repayment guidance; GOV.UK — student loan and postgraduate loan employer guidance.